

This week has been pretty quiet, with not much to do.
Unfortunately, the current market volatility just doesn’t suit our swing trading style, which is all about finding low-risk opportunities: that’s how we trade and manage the portfolio.
It’s wild to think that on March 17th, we were at our peak, up around +11% for 2026, and then a string of consecutive losses brought us down to about +2.5% today, even while the indices are negative YTD. All things considered, given what’s happening out there, we’re still fortunate to be in the green.
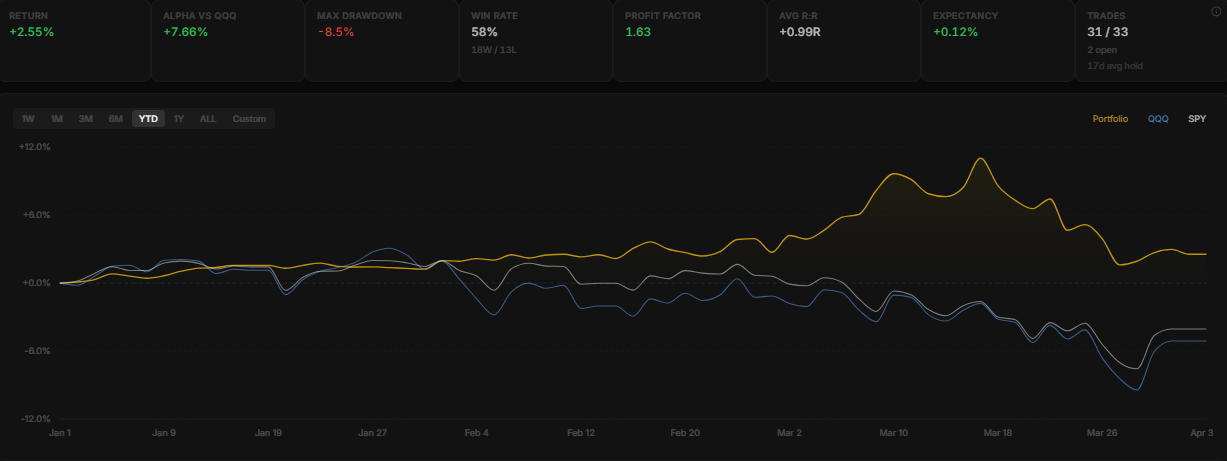
The funny part? Our most recent losses all came from stocks that ended up ripping over the past two days: DOCN, AAOI, LUNR.
But that’s fine.
The selection has been solid, our market view and themes are on point, we just need to be more defensive during downtrends. Paradoxically, during this 2–3 day push higher, we barely moved the portfolio, aside from a small starter position earlier in the week. Nothing else.
From now on, we’ll start adding a short intro to the watchlist, focusing more on how our trading week actually went (our thoughts, what’s happening behind the scenes), dialing back the “writer” tone a bit.
Hopefully, this gives you more insight into how we think and operate.
Happy Easter, everyone!
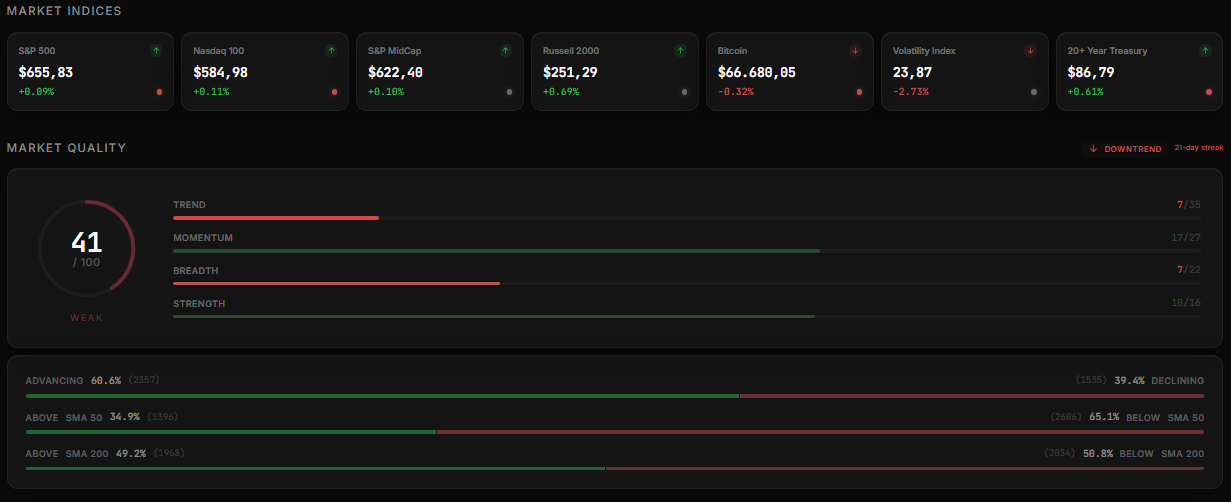
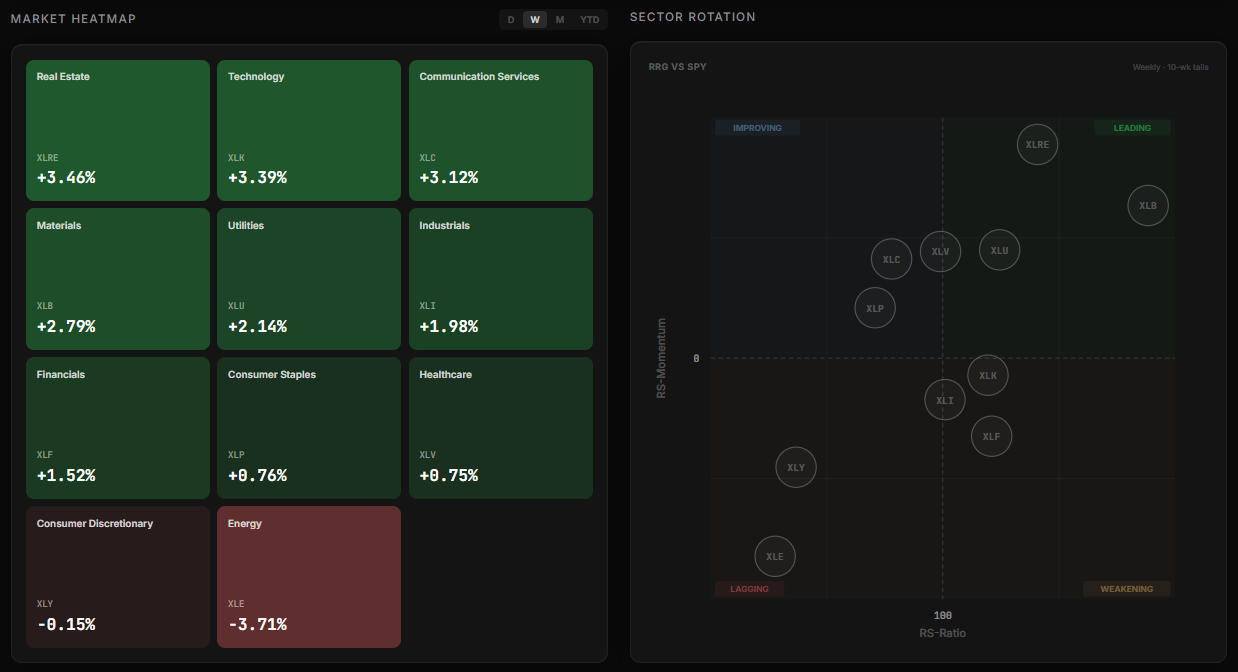
Here’s a look at this week’s market health, with a breakdown of index and sector performance.

We are currently developing an application.
It is not a generic solution for every market participant, but a platform built specifically for swing trading, momentum strategies, and short to medium-term investing.
If we see meaningful interest, we will open a limited number of testing spots and allow selected users to access the platform early.
As previously stated, all paid subscribers will receive full access to the platform at no additional cost.

Latest articles:


Each stock carries a risk badge: ⚠️ High | 📊 Medium | 🛡️ Low.
Based on volatility, float, technicals, and fundamentals. Size your positions accordingly.
📈 Free Setup: Make It Count
PLUG: Plug Power Inc ⚠️
What they do: A provider of comprehensive hydrogen solutions
Why watch? For much of its history, Plug Power has been the ultimate “story stock”, full of immense secular potential but hindered by chronic operational losses and a high rate of cash consumption. However, the narrative is shifting from theoretical promise to tangible industrial adoption. The prevailing anxieties surrounding the colossal energy requirements of the artificial intelligence buildout have forced a re-examination of every available power source. As the limitations of the current grid become apparent, hydrogen is re-emerging as a viable tool for decentralized, carbon-neutral energy, particularly for the power-hungry data centers that underpin the AI expansion.
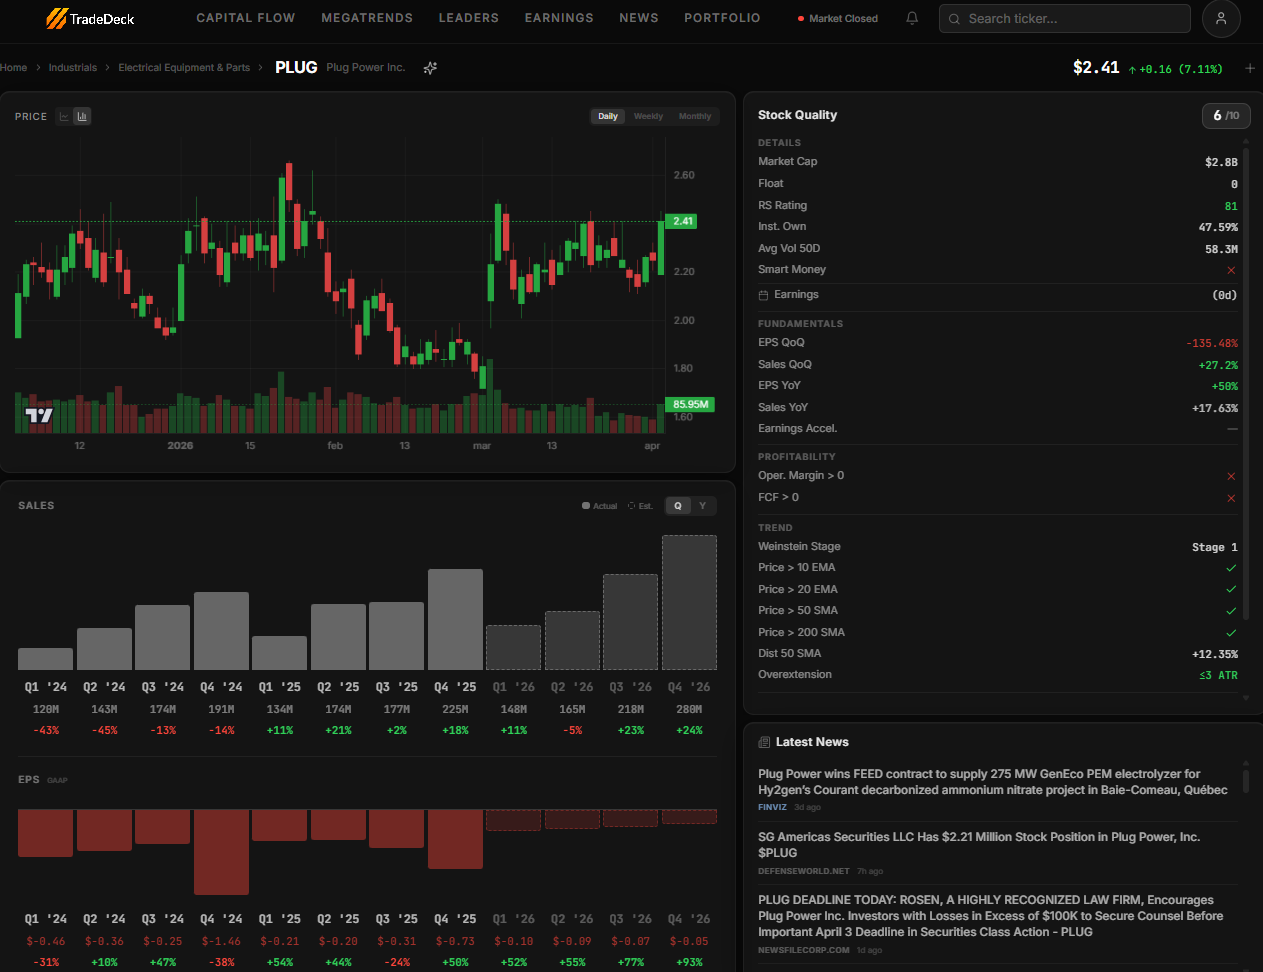
March’s earnings report provided the fundamental fuel for this shift in sentiment. The company posted a full-year revenue increase of nearly 13% year-over-year, reaching approximately $710 million. This growth was underpinned by a record $187 million contribution from its GenEco electrolyzers, which now boast a global sales funnel valued at a staggering $8 billion. With over 300 megawatts of these systems already deployed across six continents, Plug is proving it can move beyond pilot programs into large-scale commercial reality.
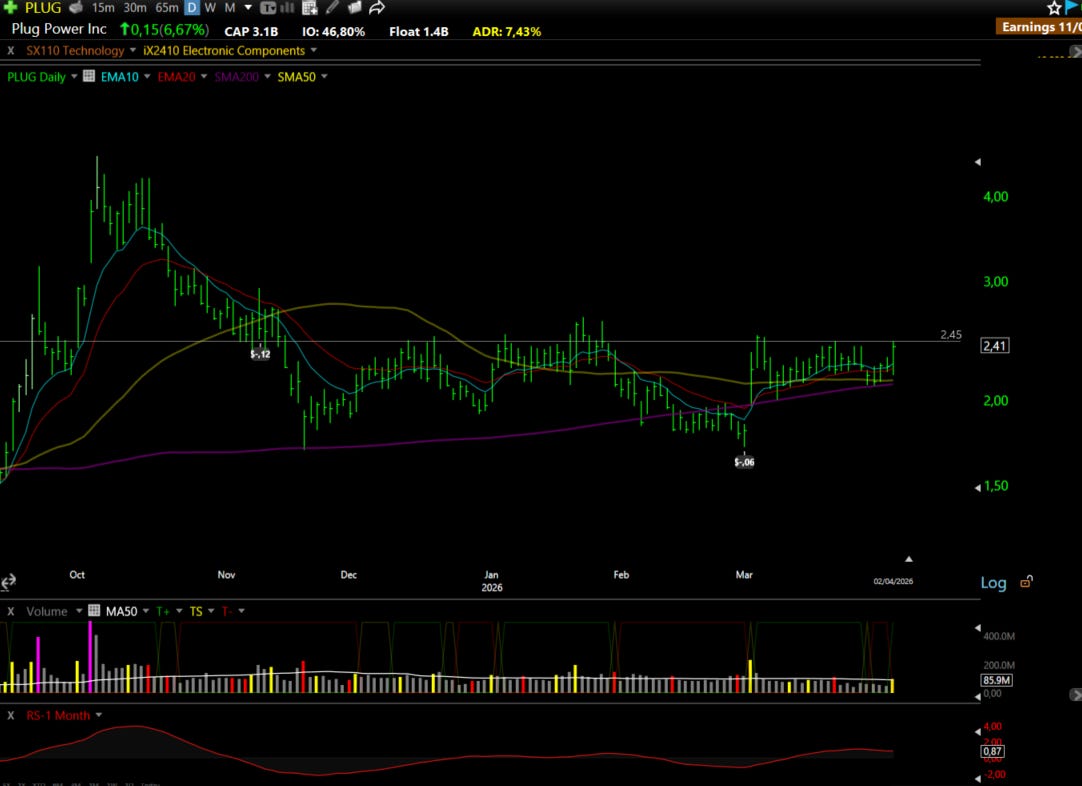
Technical Outlook: The stock has rallied roughly 40% from its recent lows, but the most compelling evidence for a turnaround is the price action around the $2.45 level. Since late 2025, this specific price point has acted as a ceiling that the stock is now aggressively testing. What makes this setup particularly high-conviction is the alignment across multiple timeframes: the $2.45 barrier is a prominent horizontal resistance level on the daily, weekly, and monthly charts simultaneously. When a stock breaks out from such a universally recognized technical level, the resulting move can be powerful. With a stop-loss positioned just beneath the recent daily lows, the setup offers a disciplined risk-reward profile for a stock that appears to be transitioning from a speculative laggard to a leader in the renewable energy thematic.
Why We Don’t Wait for Sunday
Markets don’t move on your schedule. The best low-risk entries don’t announce themselves politely and wait for the weekend newsletter.
They show up when they show up. And if you’re not positioned, you miss them.
Paid members get real-time alerts: exact entries, stops, position sizing, and the thesis behind every trade. The same information we use to manage our own capital.
Free members get just one pick on Sunday.
Does that sound like an edge to you?
What’s Inside Premium
Free Access to TradeDeck
Premium members get early access to TradeDeck, the trading platform we’re building. The value of the platform alone already exceeds the cost of the subscription.
Watchlist Elite (7-9 Stocks)
Each selection undergoes rigorous financial analysis, technical evaluation, and strategic assessment.
Full Portfolio Transparency
Every position we hold. Entry price. Current P&L. Stop level. Real money, real risk.
Real-Time Trade Alerts (Chat Access)
This is where the edge lives. Exact entries, stops, and position sizing. Real-time. No lag
Quick Picks (5 Names)
Additional setups that just missed our main criteria but are worth watching.
Chat Access
See our thought process in real time. Ask questions. Watch how we manage risk.
The Tools We Actually Use
Member discounts on TC2000, Fiscal.ai, and other platforms. Same tools, better pricing.
What Paid Members Say:
We’re entrepreneurs first, traders second. We’ve sat in the CEO chair. We know what real execution looks like and how to spot it.
€39/month or 299€/year. Less than one losing trade. Cancel anytime.
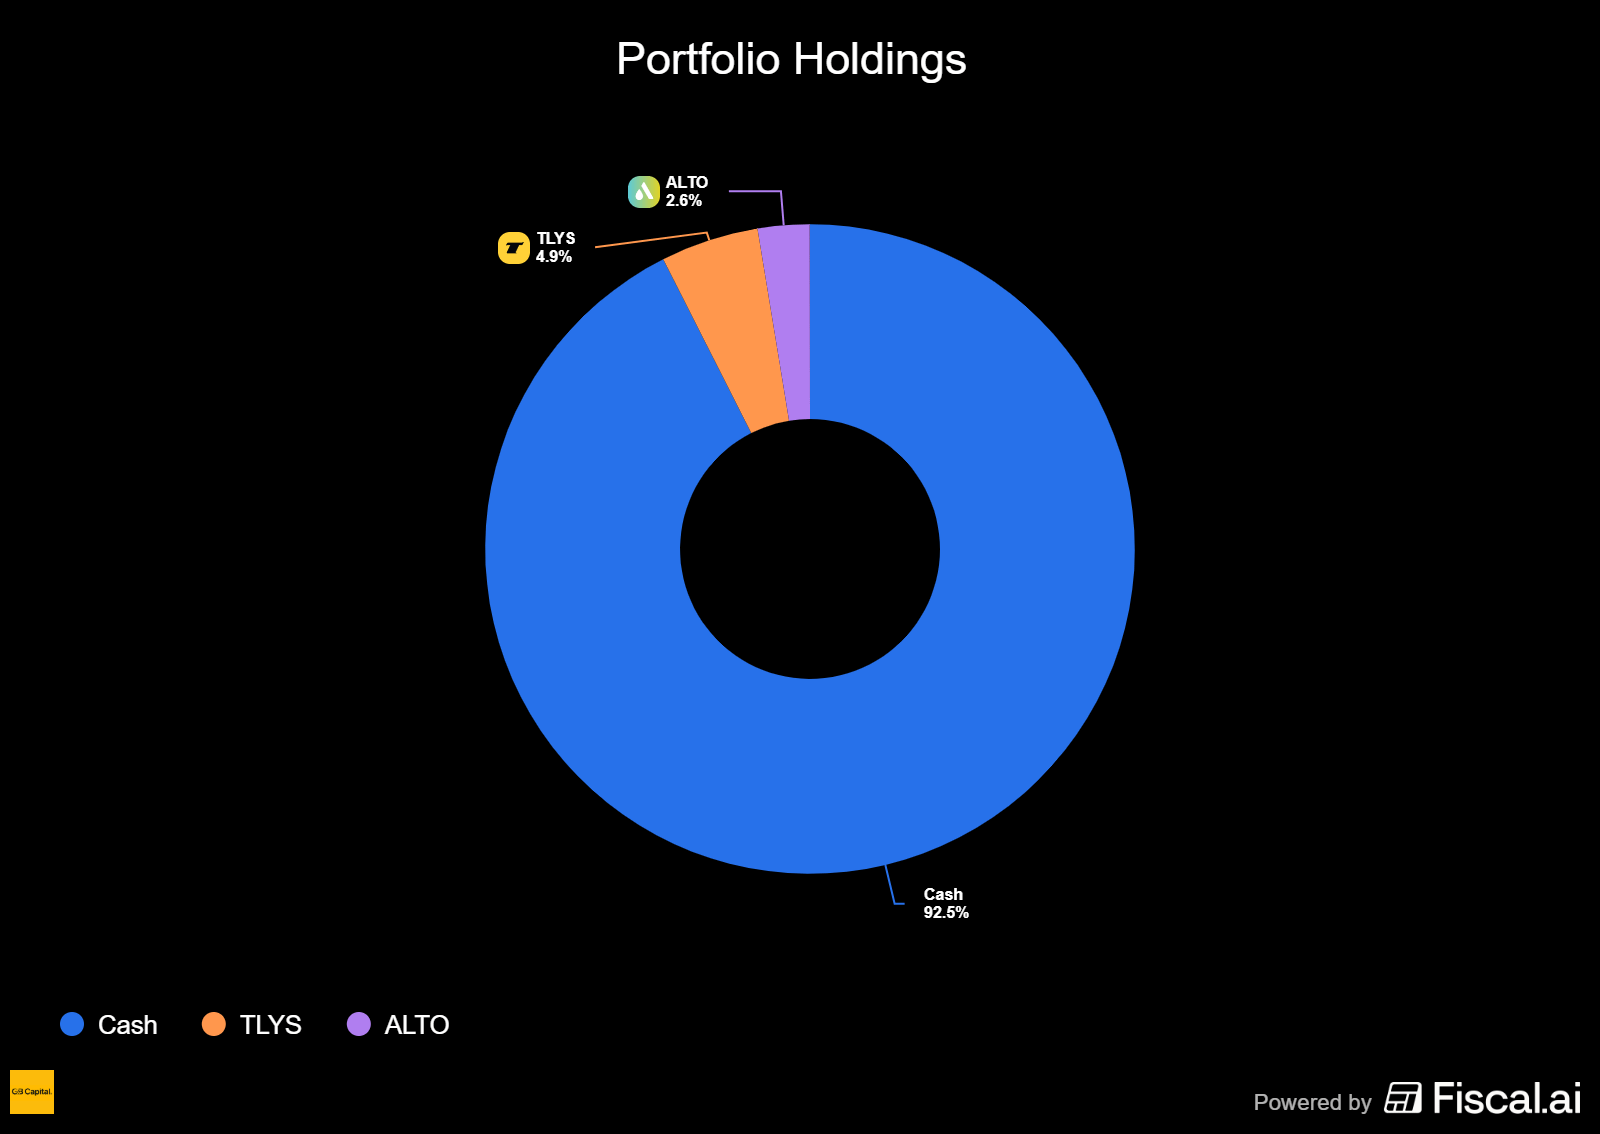
Portfolio updates and new positions:


⚡ AI-optimized, human-verified: Our expert team carefully selected Premium market intelligence from Fiscal.ai data. Explore now →
💎📈 Watchlist Elite: Premium Market Movers
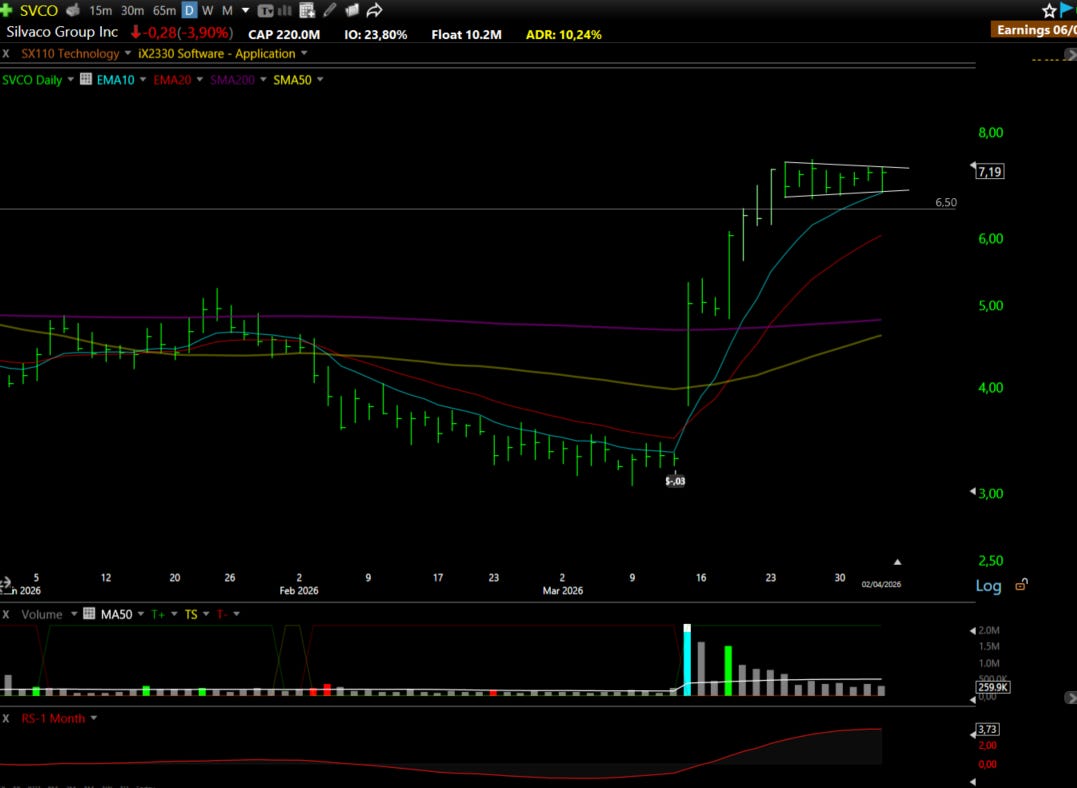
SVCO: Silvaco Group Inc ⚠️
What they do: A provider of specialized Electronic Design Automation (EDA) software
Why watch? Silvaco has long been overlooked by the broader market, often dismissed as a minor player in a sector dominated by giants. This assessment ignores the company’s critical role in the high-growth niches of silicon carbide and power electronics: technologies essential for the electric vehicle and AI infrastructure booms. The company recently solidified this positioning by expanding its strategic partnership with Taiwan’s Advanced Power Electronics Corp (APEC), which has integrated Silvaco’s design flows deep into its production of next-generation power devices.
The structural bull case here lies in the company’s FTCO platform, an AI-driven solution that optimizes fabrication processes. This product line is beginning to see meaningful adoption among major chip manufacturers, while its semiconductor IP business is providing the most immediate boost to the top line. The fourth quarter of 2025 served as a wake-up call for the market, as Silvaco delivered across-the-board beats. Bookings reached $18.3 million, hitting the high end of guidance, while revenue also outperformed expectations. Perhaps most impressive was the non-GAAP gross margin of 85.6%, a sequential improvement of 500 basis points that highlights the operating leverage inherent in their software-heavy model.
Technical Outlook: Following the earnings surprise, the stock surged 120% before entering its current consolidation phase. Critically, this pullback is occurring on significantly lower volume, suggesting that the initial buyers are not rushing for the exits and are instead waiting for the next leg higher. The stock found support at its 10-day exponential moving average last Thursday and has held steady since. With an initial price target of $10.00, traders can justify a position by risking roughly $0.50 to $0.60 to capture a potential $3.00 gain. This favorable risk-reward ratio, combined with a clear “change of character” in the price action, makes Silvaco one of the most interesting under-the-radar semiconductor plays currently available.
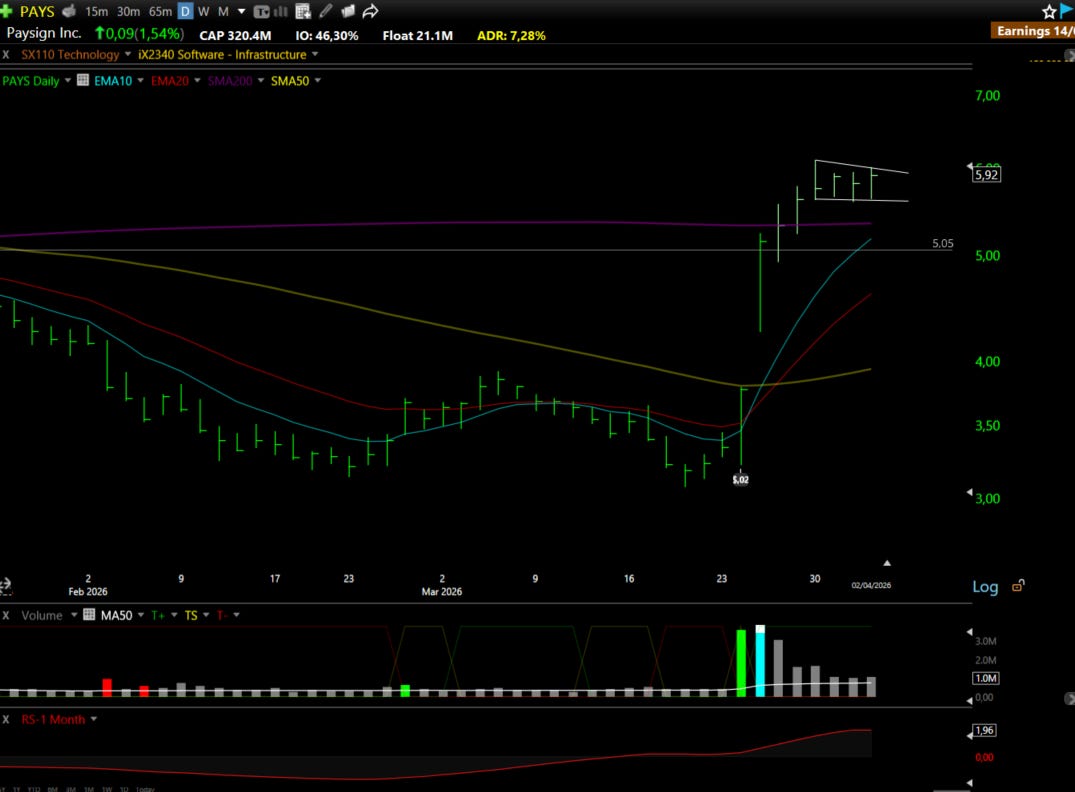
PAYS: Paysign Inc 📊
What they do: A financial technology firm providing a proprietary transaction processing platform for prepaid card programs, primarily serving the healthcare and pharmaceutical sectors
Why watch? Paysign occupies a highly defensible niche within the fintech landscape. Unlike broad-market payment processors, Paysign’s systems are deeply integrated into the specific workflows of patient affordability programs and plasma donation centers. This specialization creates a competitive moat characterized by high switching costs; once a pharmaceutical company or healthcare provider integrates Paysign’s co-pay management or enrollment systems, moving to a competitor is a disruptive and costly endeavor.
The company’s 2025 results were nothing short of exceptional. Revenue surged 40.5% to $82 million, driven by the rapid scaling of its patient affordability platform. While its legacy plasma segment remains a market leader with a 50% share, the affordability business is the true growth engine, targeting a total addressable market estimated between $500 million and $1 billion. This segment carries higher margins and provides a differentiated product in the complex world of medical co-pay management. As Paysign improves its operating leverage, the “quiet” growth of its bottom line is becoming increasingly difficult for the market to ignore.
Technical Outlook: The stock’s 90% post-earnings surge represents a definitive change in character, effectively erasing a significant portion of the decline seen since mid-2025. The move was accompanied by weekly volume six times the historical average, a massive influx of institutional capital that typically signals the start of a multi-month trend rather than a short-term spike. While current indicators suggest the stock is technically overextended (marked by light green bars on our proprietary charts), it has refused to give back any of its gains. This price “stickiness” is a sign of internal strength. We are looking for a few days of sideways consolidation or a brief “shakeout” to normalize these overbought levels before the second leg of the rally begins.

Put the market on autopilot, experience the Best Platform with TC2000
Explore now →
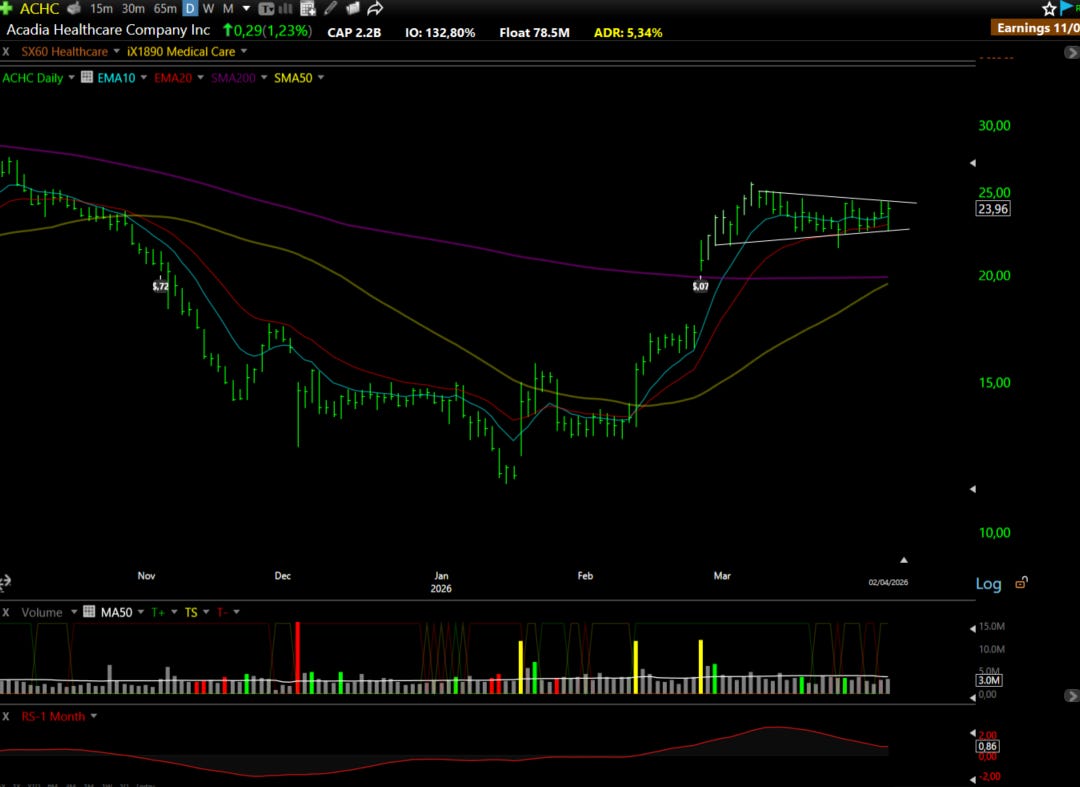
ACHC: Acadia Healthcare Company Inc 📊
What they do: An operator of behavioral healthcare facilities across the US
Why watch? Acadia is currently a classic “transformation” story. Under the leadership of CEO Debbie Osteen, the company is pivoting toward operational discipline and more prudent capital allocation after a period of industry-wide turbulence. While 2025 was a “reset” year (marked by a $1.1 billion net loss due to a non-cash goodwill impairment), the underlying business remains a cash-flow-generating machine. Revenues reached $3.3 billion, and adjusted EBITDA stood at a healthy $609 million.
The outlook for 2026 suggests modest top-line growth, as management prioritizes stability over aggressive expansion. This conservative guidance has kept many investors on the sidelines, but for contrarian thinkers, Acadia’s massive asset base and essential role in the US healthcare infrastructure provide a significant margin of safety. Behavior healthcare demand continues to outpace supply, and as Acadia resolves its structural challenges, the gap between its intrinsic value and current market price could narrow rapidly.
Technical Outlook: From a charting perspective, Acadia is acting with remarkable poise. The stock has spent the last five weeks in a tight consolidation, consistently finding support at its 10 and 20-day exponential moving averages. Zooming out to the weekly chart reveals a massive cup and handle formation, one of the most reliable bullish continuation patterns in technical analysis. We appear to be in the final stages of the handle’s completion. A breakout from this multi-week base would likely signal the start of a sustained uptrend, backed by the stabilizing fundamental story being written by the new management team.
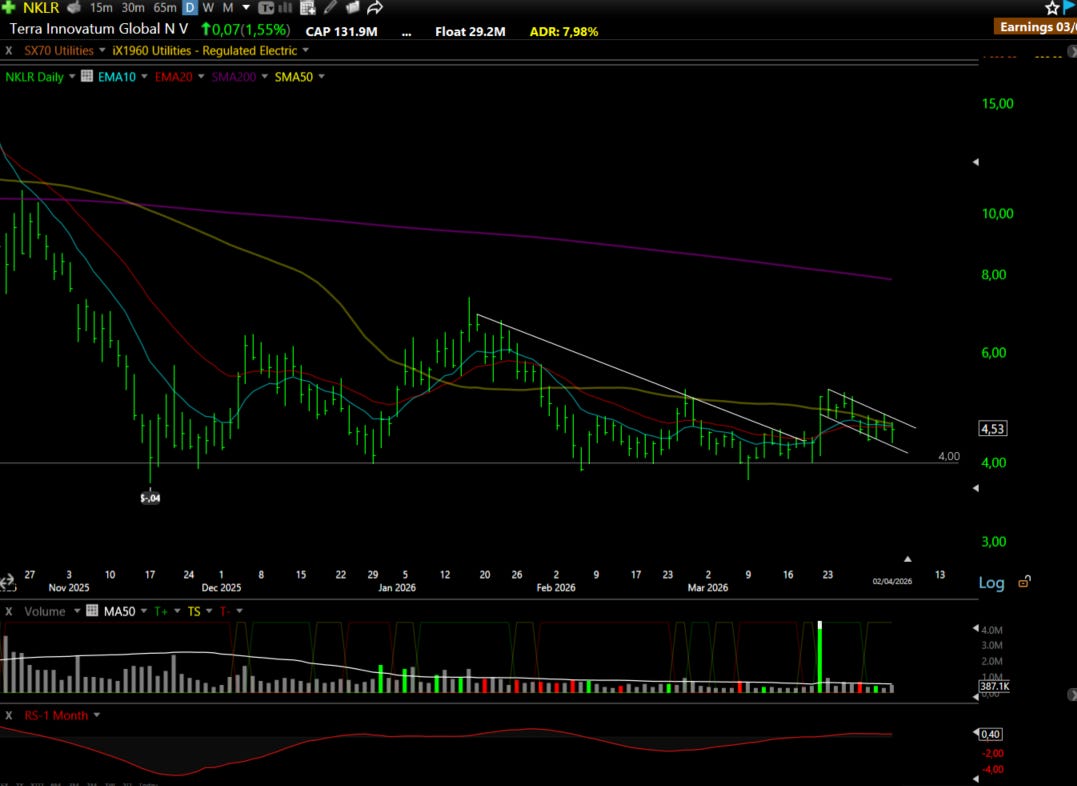
NKLR: Terra Innovatum Global NV ⚠️
What they do: A speculative energy technology firm developing micro-modular nuclear reactors
Why watch? Terra Innovatum is a pre-revenue, high-risk play on the future of energy. Much like Plug Power, it is a direct beneficiary of the “energy for AI” theme. The company’s microreactors, specifically the SOLO brand, are designed to provide constant, carbon-free power for hyperscale data centers that cannot rely solely on a stressed electric grid. While commercialization is not expected until 2027, the company is hitting its developmental milestones, having recently secured all necessary components for its first-of-a-kind deployment.
The recent appointment of Kathy Williams, a veteran of the nuclear industry and former CEO of AREVA, as CFO adds a layer of professional credibility to the executive suite as they navigate the rigorous U.S. Nuclear Regulatory Commission permitting process. From a financial standpoint, the company has enough liquidity to cover approximately three years of operations at its current burn rate. While dilution is a medium-term risk, the short-term focus is squarely on regulatory progress and the potential for a speculative rerating if the nuclear theme gains further traction with institutional investors.
Technical Outlook: The stock has established a rock-solid support level at $4.00, which serves as the invalidation point for any bullish thesis. Currently, the price is hovering just above its key moving averages (the 10, 20, and 50-day markers) all of which are acting as a springboard for a potential move higher. The stock’s refusal to break down despite a choppy broader market suggests that the path of least resistance is now to the upside. In speculative “theme” stocks like this, moves tend to be violent and rapid once they begin. Given the low entry price and clear support, the risk-reward ratio is highly attractive for those looking to play the next phase of the nuclear energy trade.
KSPI: Joint Stock Company Kaspi.kz 🛡️
What they do: A multi-national “super app” based in Kazakhstan that integrates payments, a retail marketplace, and fintech services into a single ecosystem.
Why watch? Kaspi.kz is a fintech powerhouse that dominates the daily lives of consumers in Kazakhstan and is rapidly expanding into markets like Türkiye, Azerbaijan, and Ukraine. Its business model is built on a powerful network effect: as more users join for payments, they naturally migrate to the marketplace and use Kaspi’s lending products, with each segment driving the profitability of the next. Despite its high margins and dominant market share, the stock is currently valued as if it were a low-growth utility rather than a high-growth tech platform.
The expansion into neighboring regions provides a significant “growth option” for investors. With its core Kazakh business generating consistent cash flow, the company has the dry powder to fund its regional ambitions. Furthermore, the improvement in regional commodity cycles and the turnaround of its international holdings like Hepsiburada suggest that the market is severely mispricing Kaspi’s future earnings potential. It is a rare example of a highly profitable, asset-light business trading at a significant discount to its Western peers.
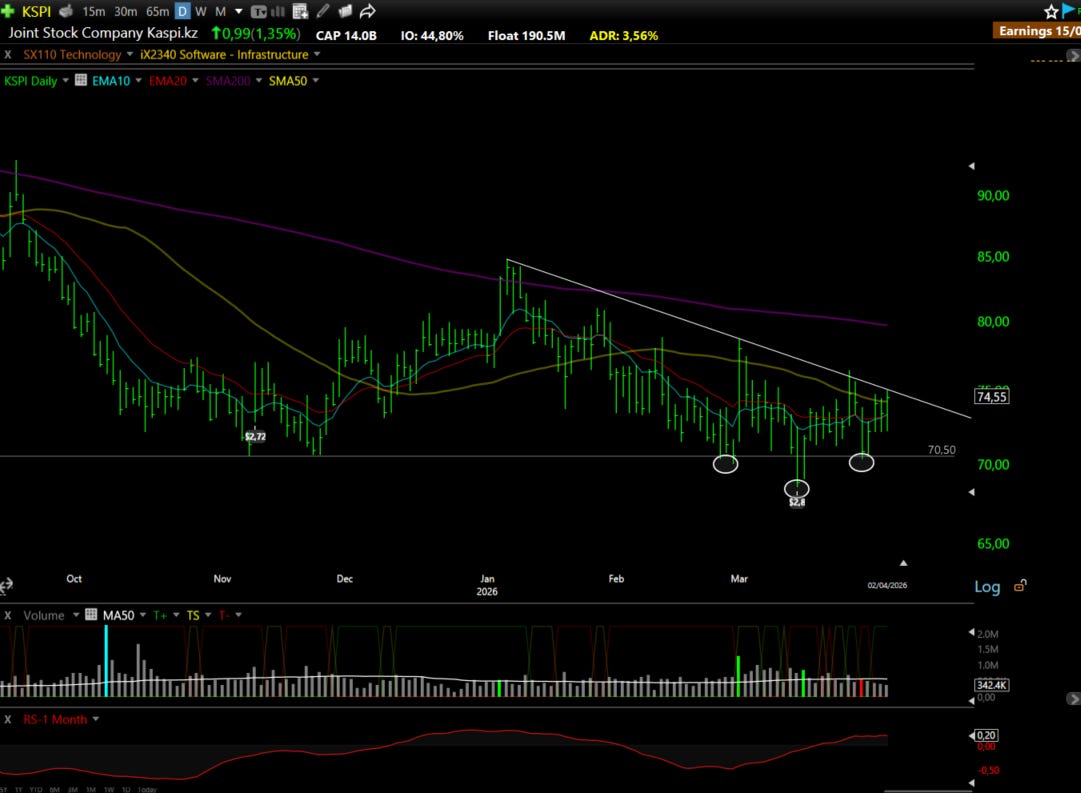
Technical Outlook: The stock has shown remarkable resilience at the $70.00 level, which has acted as a floor on no fewer than five occasions since late 2025. This refusal to trade lower suggests significant accumulation by long-term holders. On the daily chart, we can observe a clear downward trendline that, if broken, would likely trigger a fresh uptrend. The setup is particularly unique because the same patterns—a base at $70.00 and an emerging inverse head-and-shoulders formation—are visible across the daily, weekly, and monthly timeframes. With the 10 and 20-day exponential moving averages now converging and providing support, the stock appears coiled for a breakout that would align its technical picture with its robust fundamental value.
These tickers below didn’t make the main cut, but they’re on our radar for a reason. We’ve vetted them; now you decide if they fit your game.
More opportunities, less noise.
⚡📋Scanned Stocks: Quick Picks
CAST - FreeCast Inc
BIAF - bioAffinity Technologies Inc
STGW - Stagwell Inc
CRCL - Circle Internet Group Inc
IOT - Samsara Inc
“I believe in analysis and not forecasting.”
Nicolas Darvas
Disclaimer: This analysis is for informational purposes only and should not be considered financial advice. Always conduct your research and consult with a licensed financial advisor before making investment decisions.