

Greenland, Tariffs, and Three Straight Stop-Outs in 48 Hours
Is the Trade War Back? (Spoiler: Yes)
President Trump announced new tariffs on the EU and confirmed his top strategic priority: acquiring Greenland. Yes, you read that right. Greenland.
Here’s the breakdown: a 10% tariff on Denmark, Norway, Sweden, France, Germany, the UK, the Netherlands, and Finland, starting February 1st. And these tariffs will increase to 25% on June 1st and will NOT be lifted until a deal is reached on Greenland.
Not just any deal: a “complete and total purchase of Greenland,” according to Trump.
If this sounds insane, that’s because it is. But it’s also classic Trump. And if you’ve been paying attention for the last 12 months, you know exactly how this playbook works.
Trump’s Tariff Playbook: Timing, Pressure, and Theater
The trade war has become an episodic headwind. Tariffs resurface when markets least expect them, create chaos, and then slowly fade away.
This isn’t random. This is by design.
Trump’s entire negotiation strategy is centered around timing and pressure. He gives 2-3 weeks of lead time before tariffs go into effect, creating a window for a deal to be reached. His goal? For these tariffs to never actually go live. He wants a deal. He wants leverage. He wants the threat to do the work.
That’s why these announcements increasingly come on weekends, when markets are closed. It’s strategic. It’s calculated. It’s a theater.
And he pushes the threats to the edge. That’s why they work. Because they’re market-moving and world-changing, if they were to ever truly go into effect and stick.
But here’s the thing: they rarely do. The threat is the weapon.
The deal is the goal.
Senate Democrats Are Already Pushing Back
The latest news? Senate Democrats are planning to introduce legislation to block Trump’s newly announced 10% tariffs on the 8 European countries that oppose the US acquiring Greenland.
Will it pass? Who knows. But the buzz is building. And if this drama continues, you'd better have a good list of rare earth stocks in your watchlist.
Because next week? Those stocks are going to be the best way to profit from this madness. Probably alongside an emotional gap down on Tuesday when the market digests the news.
We have at least 1-2 names in our watchlist linked to this theme. But here’s the smarter play: adjacent stocks.
Sometimes, if you play stocks in adjacent sectors connected to basic materials and, in particular, rare earth, you’ll find names that aren’t already widely covered by investors. And that’s where you find the highest movers.
Everyone’s going to pile into the obvious plays.
But the real money? It’s in the names that fly under the radar.
Last Week We Said Opportunities Were Shrinking. This Week Confirmed It.
Last week, we told you the watchlist wasn’t great. Opportunities were shrinking. Not much was setting up.
This week? We got confirmation. The hard way.
Three stocks bought. Three times stopped out. In less than 48 hours.
Are we suddenly terrible investors? Or is the market trying to tell us something?
We’re betting on the latter.
We started this week unloading our winning positions. Why? Because a pullback is likely. Especially with this Trump tariff drama back on the table.
And honestly? A pullback would be healthy. The market’s been running hot. Too hot.
Look at the data: T2118 closed this week at 83.08. The overheat level? 90.00. We’re not there yet, but we’re close. Close enough to start thinking about it.
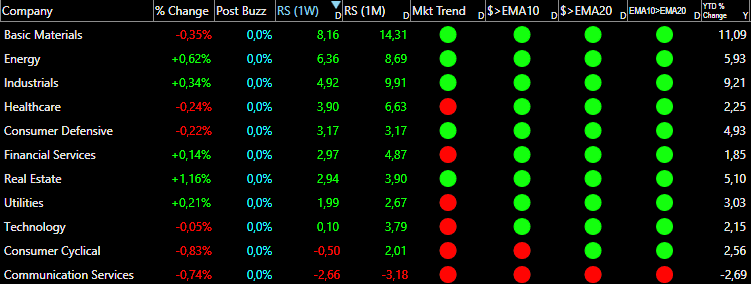
And if you check the consumer defensive sector, you’ll see six straight days of gains. Six. That’s not normal. That’s a warning sign.
That’s the market saying, “Maybe I should take a breather.”
Can this rally continue without at least a pullback? Maybe. But we’re not betting on it.
Not Satisfied With Our Trading Week
Let’s be honest: we’re not satisfied with this week. Three stop-outs in 48 hours? That’s not the standard we hold ourselves to.
So we’re using the holiday in the market to analyze our work. To figure out what went wrong. To be more cautious next week.
We want to stay on top of our game. Every week. Every month. Every year. That’s the goal. That’s the standard.
And when we fall short, we don’t make excuses. We adjust.

Latest articles:


Each stock carries a risk badge: ⚠️ High | 📊 Medium | 🛡️ Low.
Based on volatility, float, technicals, and fundamentals. Size your positions accordingly.
📈 Free Setup: Make It Count
BIDU: Baidu incorporated 🛡️
What they do: A leading Chinese technology company operating the country's dominant search engine
Why watch? Baidu just announced plans to spin off Kunlunxin, its semiconductor chip unit, and has officially filed an IPO application with the Hong Kong Stock Exchange. Kunlunxin produces AI-optimized semiconductors designed specifically for enterprise customers to run large language models and other AI workloads, positioning it as China’s answer to NVIDIA in the domestic AI infrastructure buildout. The IPO is likely to see strong demand from investors, given the market’s demonstrated appetite for AI-related offerings in China and the strategic importance of semiconductor self-sufficiency in the region. Like other large-scale cloud platforms such as Alibaba, Baidu has developed its own in-house AI chips and computing platforms that enterprise customers use to build, train, and deploy their own models. This vertical integration gives Baidu control over its AI stack and reduces dependence on foreign chip suppliers, a critical advantage as China pursues its strategic goal of making its domestic semiconductor industry more independent from Western vendors. The Kunlunxin spinoff could unlock significant value by allowing the market to separately value Baidu’s AI chip business, which has been embedded within the broader corporate structure. It also provides Kunlunxin with dedicated capital and management focus to scale production and compete more aggressively in China’s rapidly growing AI chip market. Beyond the spinoff, Baidu remains a core beneficiary of China’s AI infrastructure buildout, with its Ernie large language model gaining traction among enterprise customers and its Apollo autonomous driving platform continuing to expand commercially. If China emerges as a major investment theme in 2026 (driven by stimulus measures, AI adoption, or geopolitical repositioning), Baidu is positioned to be one of the primary beneficiaries and potential market leaders, arguably offering better risk-reward than Alibaba at current valuations.
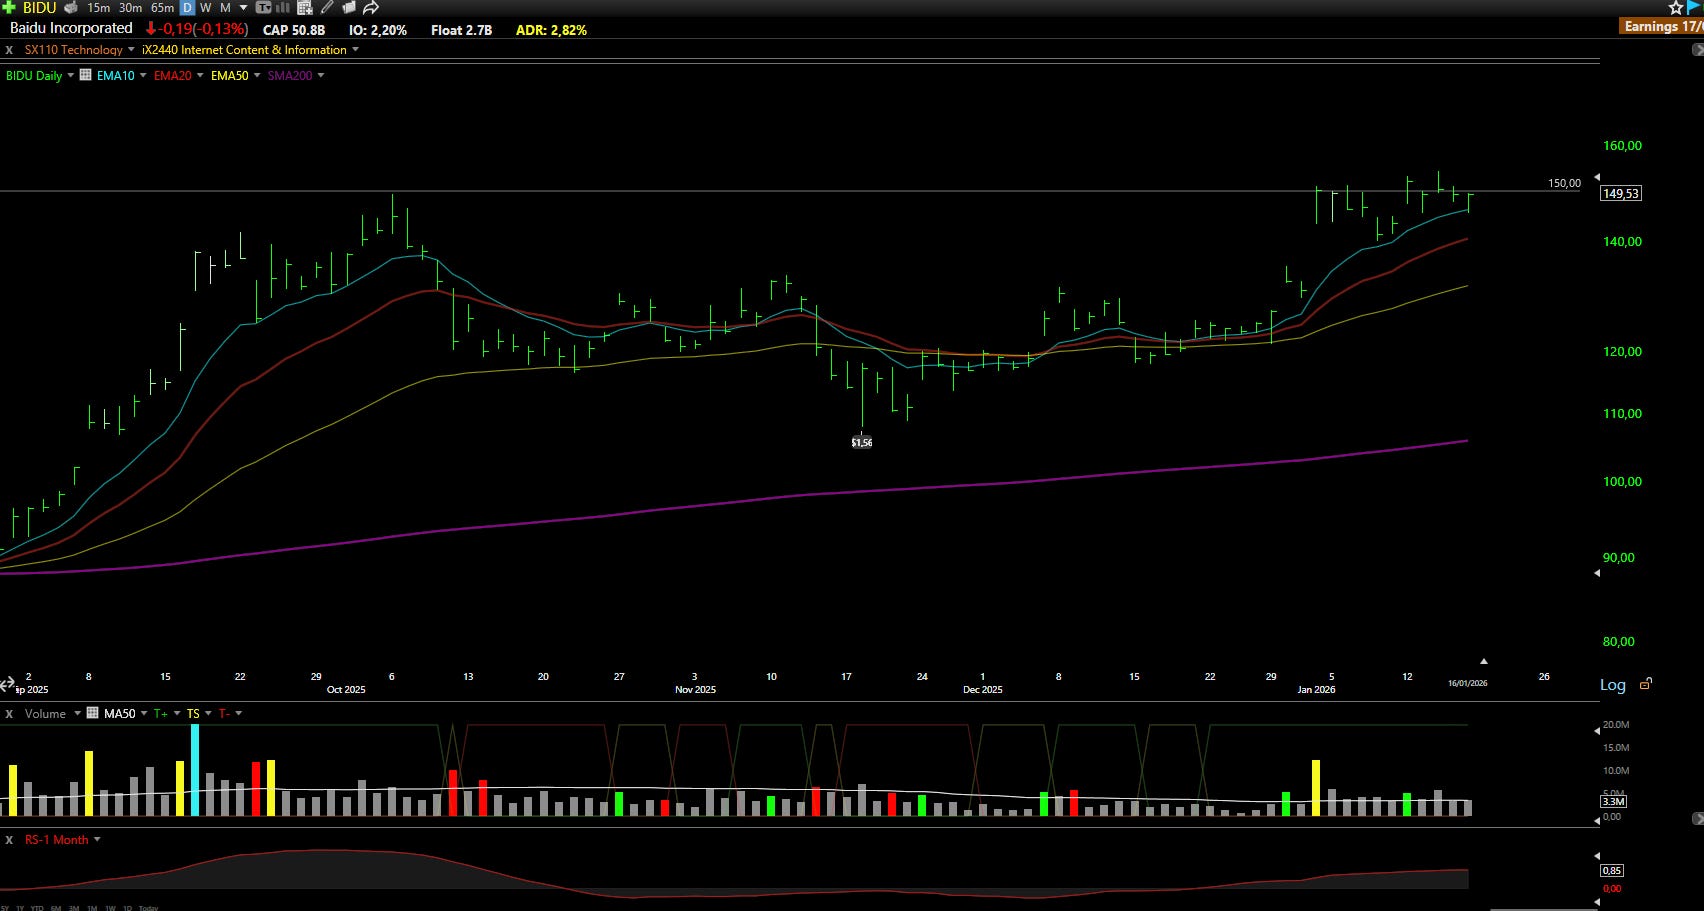
Technical Outlook: The stock approached the $150.00 level in October and was sharply rejected. In January, the stock has already made two attempts to push above this resistance without success, but notably, the 10-day exponential moving average has provided support on both pullbacks, a sign of underlying demand. The stock is now setting up for a third attempt at breaking $150.00. If this attempt succeeds on strong volume, it could mark the beginning of a new long-term uptrend. The key question is whether the third time will be the charm. If you believe China can be one of the dominant themes of 2026, Baidu is likely to be among the leaders, if not the leader, in the technology sector.
Why We Don’t Wait for Sunday
Markets don’t move on your schedule. The best low-risk entries don’t announce themselves politely and wait for the weekend newsletter.
They show up when they show up. And if you’re not positioned, you miss them.
Paid members get real-time alerts: exact entries, stops, position sizing, and the thesis behind every trade. The same information we use to manage our own capital.
Free members get just one pick on Sunday.
Does that sound like an edge to you?
What’s Inside Premium
📊 Watchlist Elite (7-9 Stocks)
Each selection undergoes rigorous financial analysis, technical evaluation, and strategic assessment.
💼 Full Portfolio Transparency
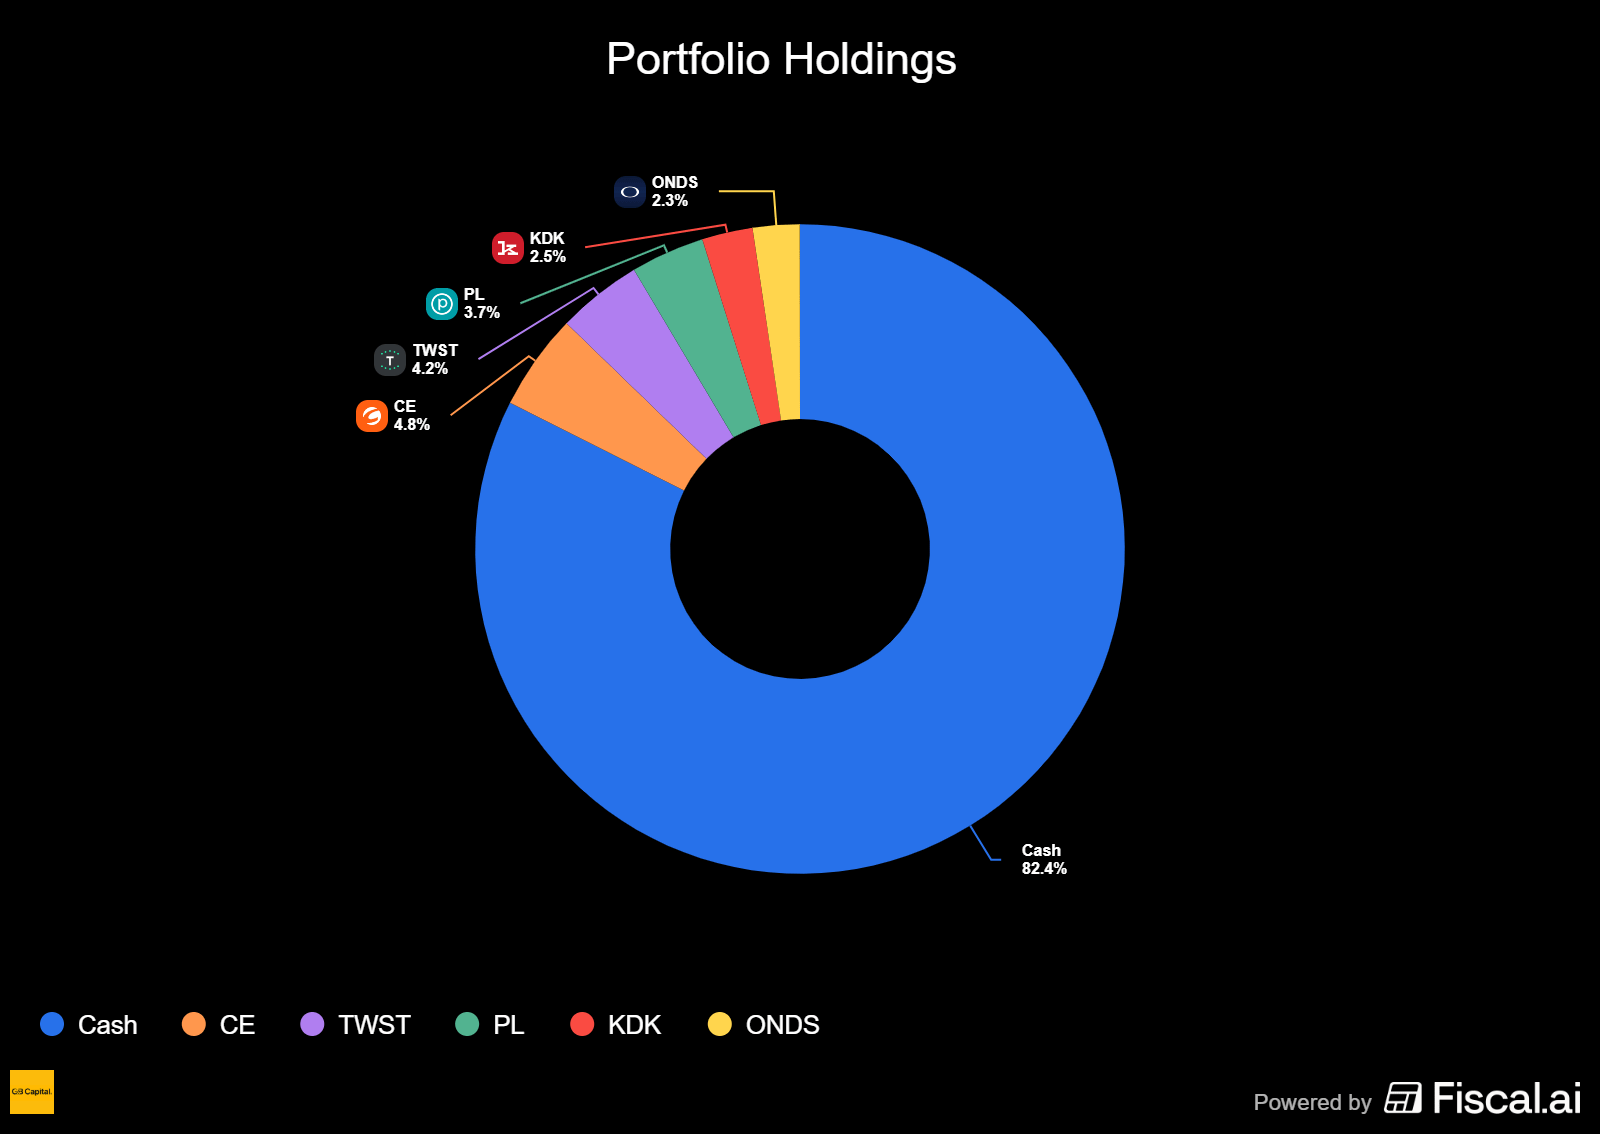
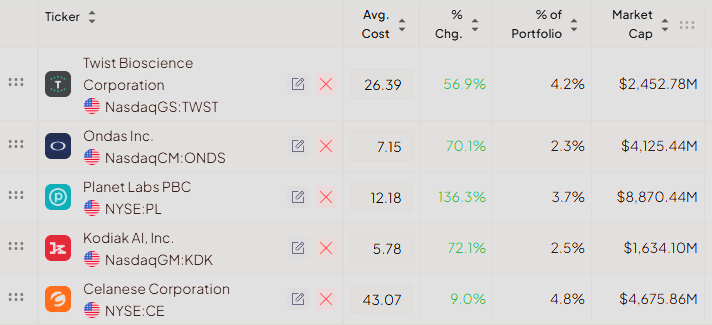
Every position we hold. Entry price. Current P&L. Stop level. Real money, real risk.
⚡ Real-Time Trade Alerts (Chat Access)
This is where the edge lives. Exact entries, stops, and position sizing. Real-time. No lag
🎯 Quick Picks (5 Names)
Additional setups that just missed our main criteria but are worth watching.
💬 Chat Access
See our thought process in real time. Ask questions. Watch how we manage risk.
🛠️ The Tools We Actually Use
Member discounts on TC2000, Fiscal.ai, and other platforms. Same tools, better pricing.
What Paid Members Say:
We’re entrepreneurs first, traders second. We’ve sat in the CEO chair. We know what real execution looks like and how to spot it.
€39/month or 299€/year. Less than one losing trade. Cancel anytime.
Portfolio updates and new positions:

⚡ AI-optimized, human-verified: Our expert team carefully selected Premium market intelligence from Fiscal.ai data. Explore now →
💎📈 Watchlist Elite: Premium Market Movers
OPTX: Syntec Optics Holdings Inc ⚠️
What they do: A U.S.-based precision manufacturer of optical and photonic components serving defense, aerospace, satellite, and emerging technology markets
Why watch? Syntec Optics occupies a strategically valuable position at the intersection of multiple high-growth secular trends while benefiting from a powerful geopolitical tailwind. The company specializes in manufacturing the precision optical components that enable everything from low-Earth-orbit satellite constellations to soldier-worn augmented reality systems: markets experiencing explosive growth as defense modernization and commercial space infrastructure accelerate. Think of Syntec as the company that makes the “eyes” for next-generation military equipment and the optical backbone for satellite internet networks like Starlink. What sets Syntec apart is its dominance in polymer optics, a specialized manufacturing technique that allows for lighter, more cost-effective optical components compared to traditional glass. The company is the largest independent custom manufacturer of polymer optics in the United States and offers a rare end-to-end capability: it can take a customer from initial design through tooling, molding, nanomachining (extremely precise material removal at microscopic scales), thin-film coatings, and final assembly, all under one roof. This integrated approach reduces lead times and gives Syntec deep visibility into customer requirements, often embedding the company early in multi-year defense programs. The recently passed National Defense Authorization Act explicitly directs the Department of Defense to develop domestic alternatives for optical components currently sourced from China and other non-aligned nations, creating a legislative mandate that directly benefits Syntec’s onshore manufacturing footprint. Beyond its established defense and satellite revenue streams, Syntec is also positioned in several nascent but potentially transformative markets: data center optics for high-speed communications, hyperspectral imaging (technology that captures light across dozens of wavelengths to identify materials and detect threats), advanced rocket propulsion systems, and even fusion energy projects. While these markets remain early-stage, they provide meaningful long-duration optionality as commercialization progresses. Importantly, the company is beginning to climb the value chain by developing complete optical subsystems rather than simply supplying individual components, a shift that typically commands higher margins and deeper customer relationships. With 82% ownership held by the CEO and Chairman (who maintains close ties to MIT’s photonics research lab), Syntec benefits from aligned leadership and access to cutting-edge academic research. As defense budgets expand, satellite constellations proliferate, and supply chain security becomes a national priority, Syntec is uniquely positioned to capture an outsized share in a market where domestic manufacturing capability is increasingly non-negotiable.
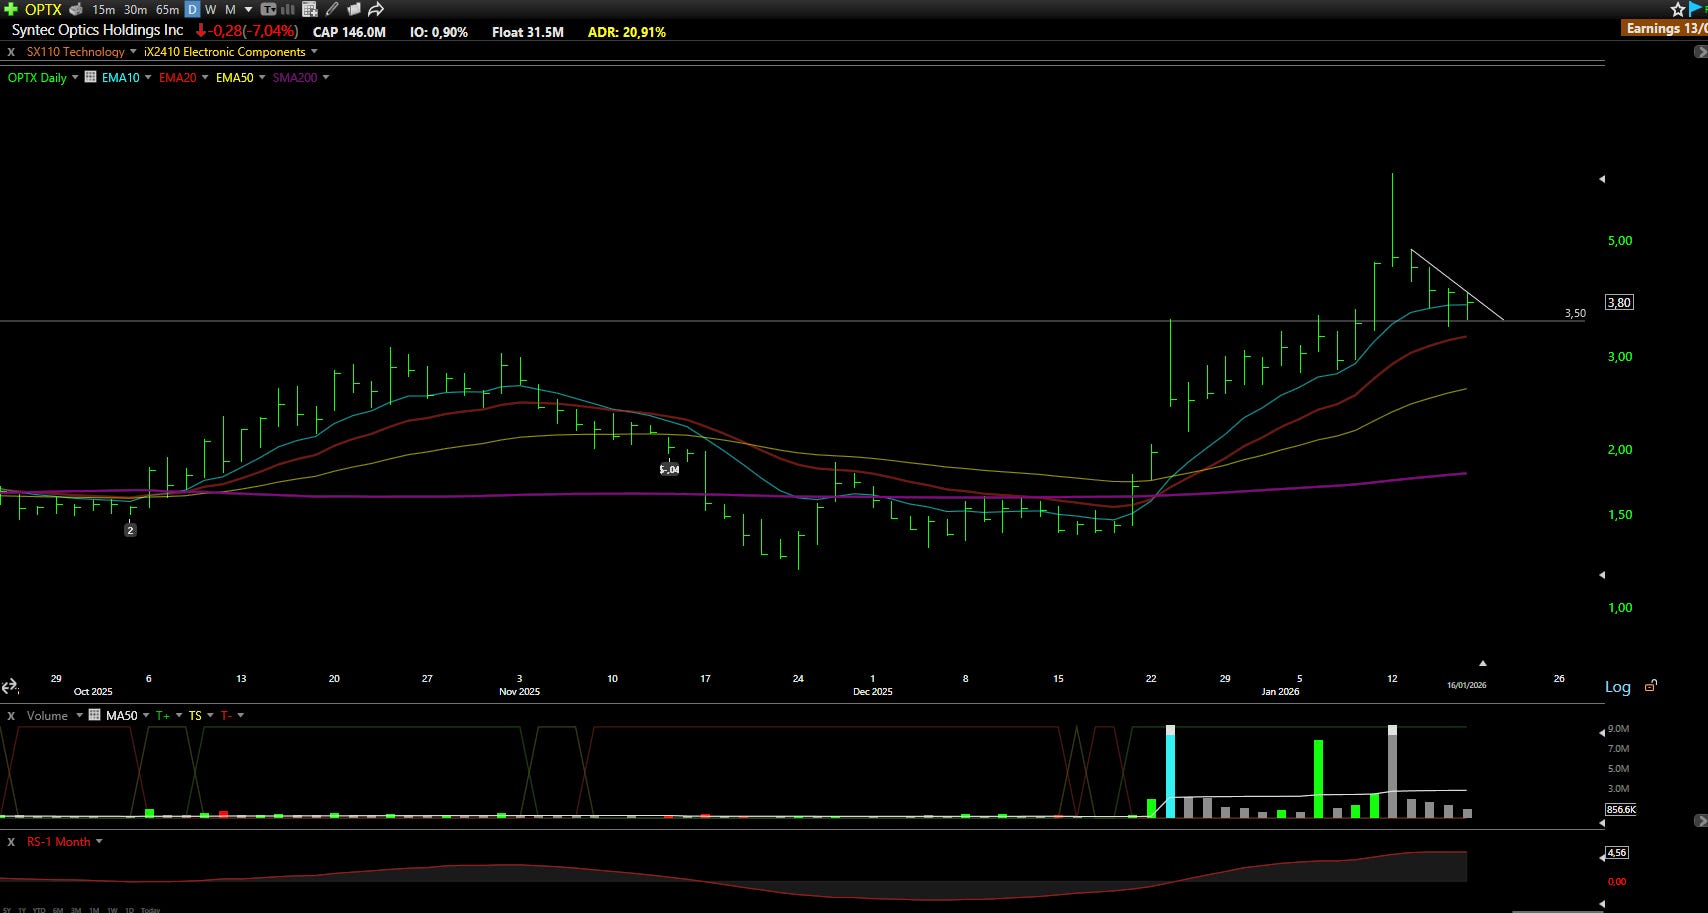
Technical Outlook: The stock recently found support at $3.50, a former resistance level in 2024 that has now flipped to support, holding firm for two consecutive days. The 10-day exponential moving average is also providing technical support beneath current prices. However, this is an exceptionally volatile trading vehicle with an average daily range exceeding 20%, meaning the stock can swing violently in either direction without warning. If you’re considering a position, treat this with extreme caution: use wider-than-normal stop losses and allow significant wiggle room to avoid getting shaken out by routine intraday noise. A well-timed entry near support could deliver rapid appreciation, but finding a low-risk entry on a stock this volatile is challenging and may require multiple attempts. This is not a stock for conservative traders or those uncomfortable with large daily swings.
UAMY: US Antimony Corporation ⚠️
What they do: The only domestic, permitted processor of antimony products in the United States
Why watch? US Antimony sits at the center of a rare convergence: surging commodity prices, geopolitical supply chain realignment, and explicit government support for domestic critical mineral production. Antimony is a niche industrial metal, but it plays an outsized role in modern defense and manufacturing. It’s used in ammunition primers, flame retardants, advanced batteries, and various military applications, making it a material the U.S. government formally recognizes as “critical” to national security. The problem? Global supply is overwhelmingly concentrated in China and Russia, which together control the vast majority of production and processing. This concentration has made antimony a flashpoint in the broader conversation around supply chain resilience, and US Antimony is the only company in the United States with permitted processing capacity to produce finished antimony products domestically. What makes the story compelling today is that this is no longer just a theoretical national-security narrative. The company has already secured a sole-source contract with the U.S. Defense Logistics Agency to supply antimony metal ingots for the National Defense Stockpile, a multi-year agreement that provides revenue visibility and validates the strategic importance of UAMY’s operations. In total, the company has locked in transformative contracts worth over $350 million, including a $245 million DLA deal and a $106 million industrial supply agreement, underpinning explosive revenue guidance for 2025 and 2026. Revenue growth has been dramatic. In the third quarter of 2025, UAMY reported approximately $8.7 million in total revenue, up from roughly $2.6 million in the prior-year quarter: a more than threefold increase. For the first nine months of 2025, revenue reached $26.23 million, representing a 182% increase year over year, with antimony sales specifically up 235%. Importantly, this growth was driven primarily by pricing rather than volume: average realized antimony prices increased more than 300% year over year, reflecting global supply constraints and heightened demand from industrial and defense customers. As geopolitical tensions persist and the U.S. government continues prioritizing domestic sourcing of critical minerals, UAMY’s strategic relevance (and pricing power) is likely to remain elevated. The company has capitalized on this opportunity by expanding operations and securing long-term offtake agreements that lock in revenue well into the future. With antimony prices remaining structurally elevated and government procurement accelerating, US Antimony has moved into a new phase of its lifecycle: from speculative mining play to revenue-generating strategic supplier.
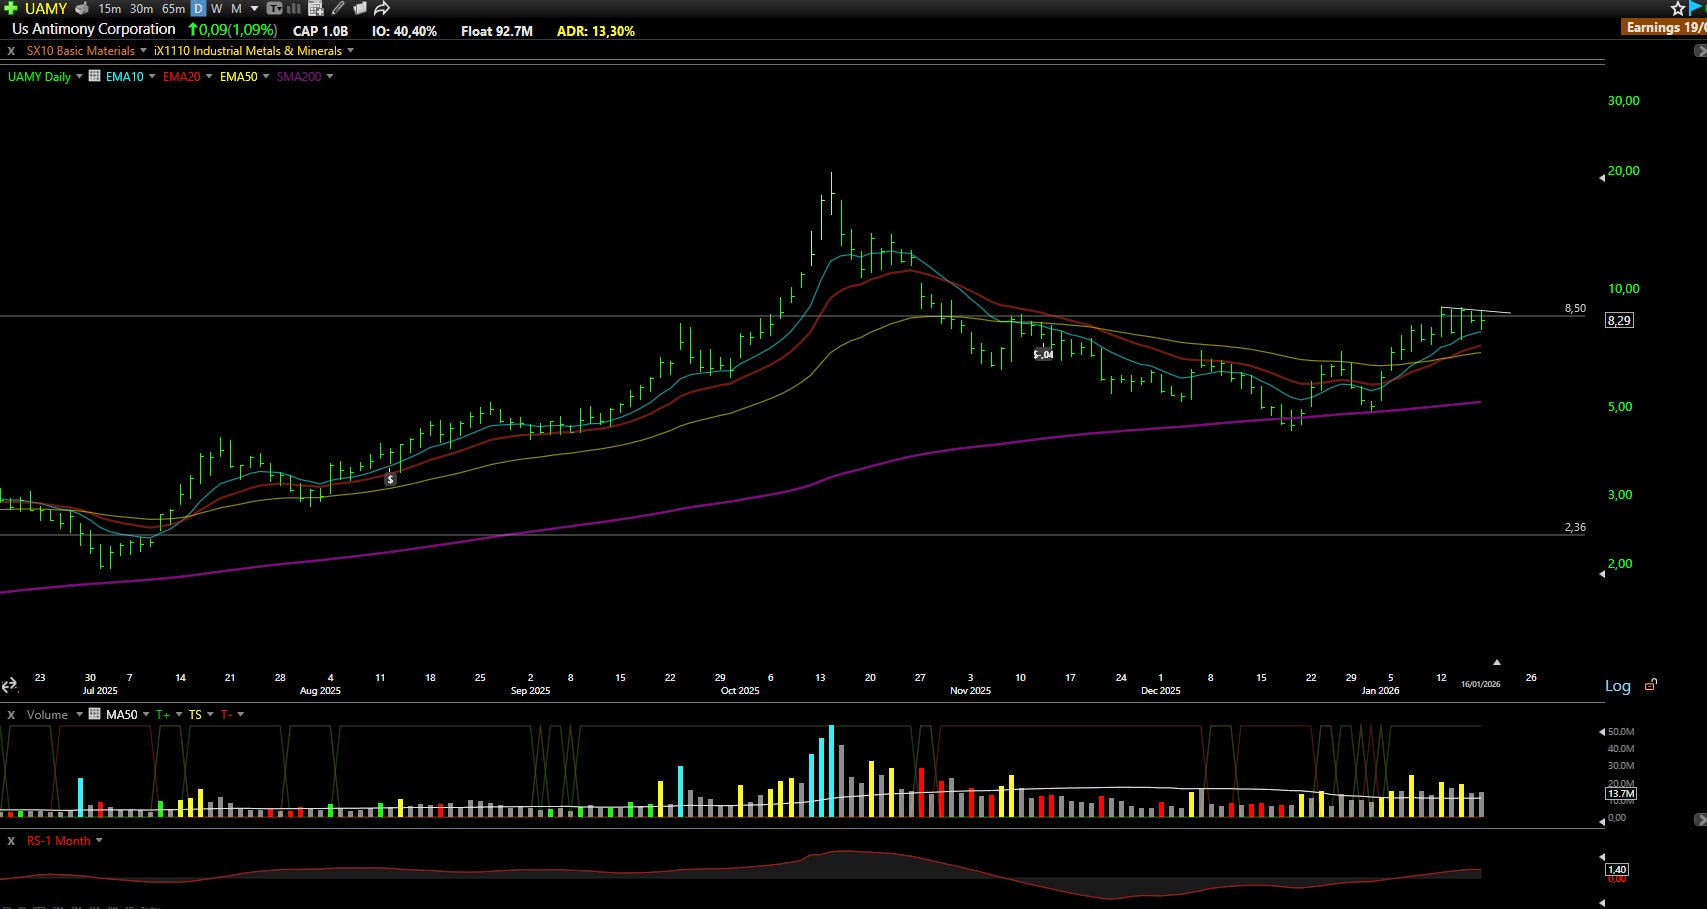
Technical Outlook: The stock is consolidating nicely below $8.50, a key resistance level established in November. After completing a cup-shaped base, the stock is now forming a handle above the 10-day exponential moving average, a classic bullish continuation pattern. Recent news around Greenland and critical minerals could trigger a gap-up in the coming days, but the key technical trigger to watch is a decisive break above $8.50 on strong volume. If the stock can reclaim and hold above this level, it would confirm the next leg higher and open the door to a significant move. Until then, the consolidation provides an opportunity to accumulate near support with a clearly defined risk level.

Put the market on autopilot, experience the Best Platform with TC2000
Explore now →
ABAT: American Battery Technology Company ⚠️
What they do: Develop lithium-ion battery recycling technologies and own mineral deposits containing battery-grade lithium
Why watch? American Battery Technology is inching slowly toward profitability while sitting on large-scale mineral deposits that are becoming increasingly valuable as electrification accelerates. Developing these assets requires significant capital, and the company has received support from the Department of Energy. Revenues from its recycling business surged 364% to $937,000 last quarter, though the company remains in heavy investment mode with a net loss of $10.3 million, still a $1.4 million improvement year-over-year. This is primarily a story stock and a volatile trading vehicle for short-term swings in the battery and EV space. The stock surged 300% in a single month back in September 2025, demonstrating its explosive potential, but also its risk. If you can identify low-risk entry points, profits can be substantial. Additionally, anything labeled “American” in the supply chain is likely to benefit from the current administration’s push to onshore critical mineral and battery production, particularly as trade tensions and supply chain security concerns intensify. The company’s Nevada-based lithium deposits and domestic recycling operations position it as a potential beneficiary of federal incentives and procurement preferences favoring domestic battery supply chains.
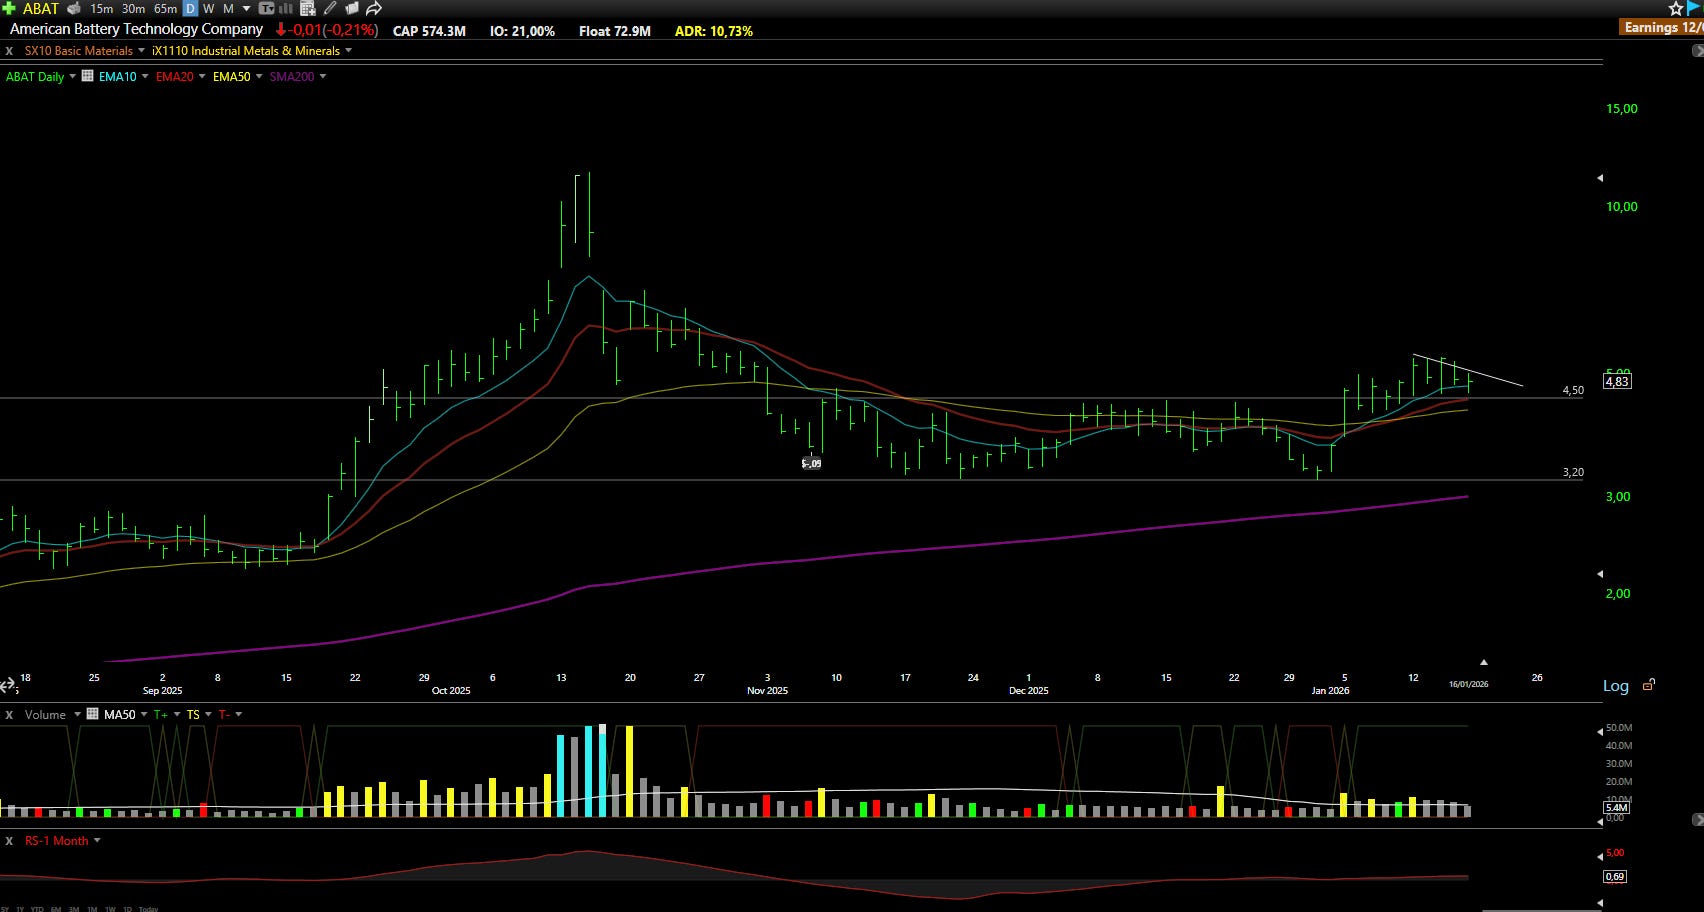
Technical Outlook: The stock recently formed a triple bottom with $3.20 serving as a key support level that has held multiple times. The stock is now trading above all major moving averages and consolidating nicely above $4.50, a former resistance level that has now flipped to support. The ideal scenario would be further consolidation above $4.50 on declining volume, or a gap down to $4.50 followed by a quick recovery and breakout above $5.00. Either setup would offer a defined-risk entry with strong reward potential. Given the stock’s history of explosive moves, patience in waiting for the right technical setup is critical.
OM: Outset Medical Inc ⚠️
What they do: A medical technology company transforming dialysis treatment
Why watch? Outset Medical is quietly trying to execute a turnaround that could redefine its trajectory. The company’s Tablo system represents a genuine innovation in dialysis care: it combines water purification and on-demand dialysate production (the fluid used to filter blood during dialysis) into a single, integrated machine that connects seamlessly with electronic medical records and a proprietary data analytics platform. This design reduces the logistical complexity and infrastructure requirements of traditional dialysis, making it easier for hospitals and clinics to “insource” dialysis treatment rather than outsourcing patients to specialized centers. More than 1,000 U.S. healthcare facilities now use Tablo, performing roughly 1 million treatments per year and more than 3 million cumulative treatments since launch. Revenue in the fourth quarter totaled approximately $28.9 million, bringing full-year 2025 revenue to approximately $119.5 million: a 5% increase over 2024. While top-line growth remains modest, the real story is operational discipline and cash flow improvement. The company reduced annual cash burn from $116 million in 2024 to under $50 million in 2025, a massive fundamental win for a growth-stage medical technology company. This dramatic reduction in cash consumption extends the company’s runway and reduces dilution risk, making it far more attractive to investors. Additionally, Outset has successfully shifted its business model toward recurring revenue, with approximately 70% of revenue now coming from consumables and services rather than one-time equipment sales, a transition that typically commands higher valuations in med-tech. Year-end cash, including restricted cash, cash equivalents, and short-term investments, totaled $173 million, providing ample liquidity to fund operations and growth initiatives. Management has expressed confidence entering 2026, citing a strong backlog, a growing pipeline of new opportunities, and plans to deliver new services and technologies that continue to improve patient outcomes with lower cost and less complexity than traditional dialysis. Compared to peers, Outset appears undervalued, particularly given its improving unit economics and potential for margin expansion as the installed base scales. This is a possible turnaround play with improving fundamentals and a differentiated product in a large and usually stable market.
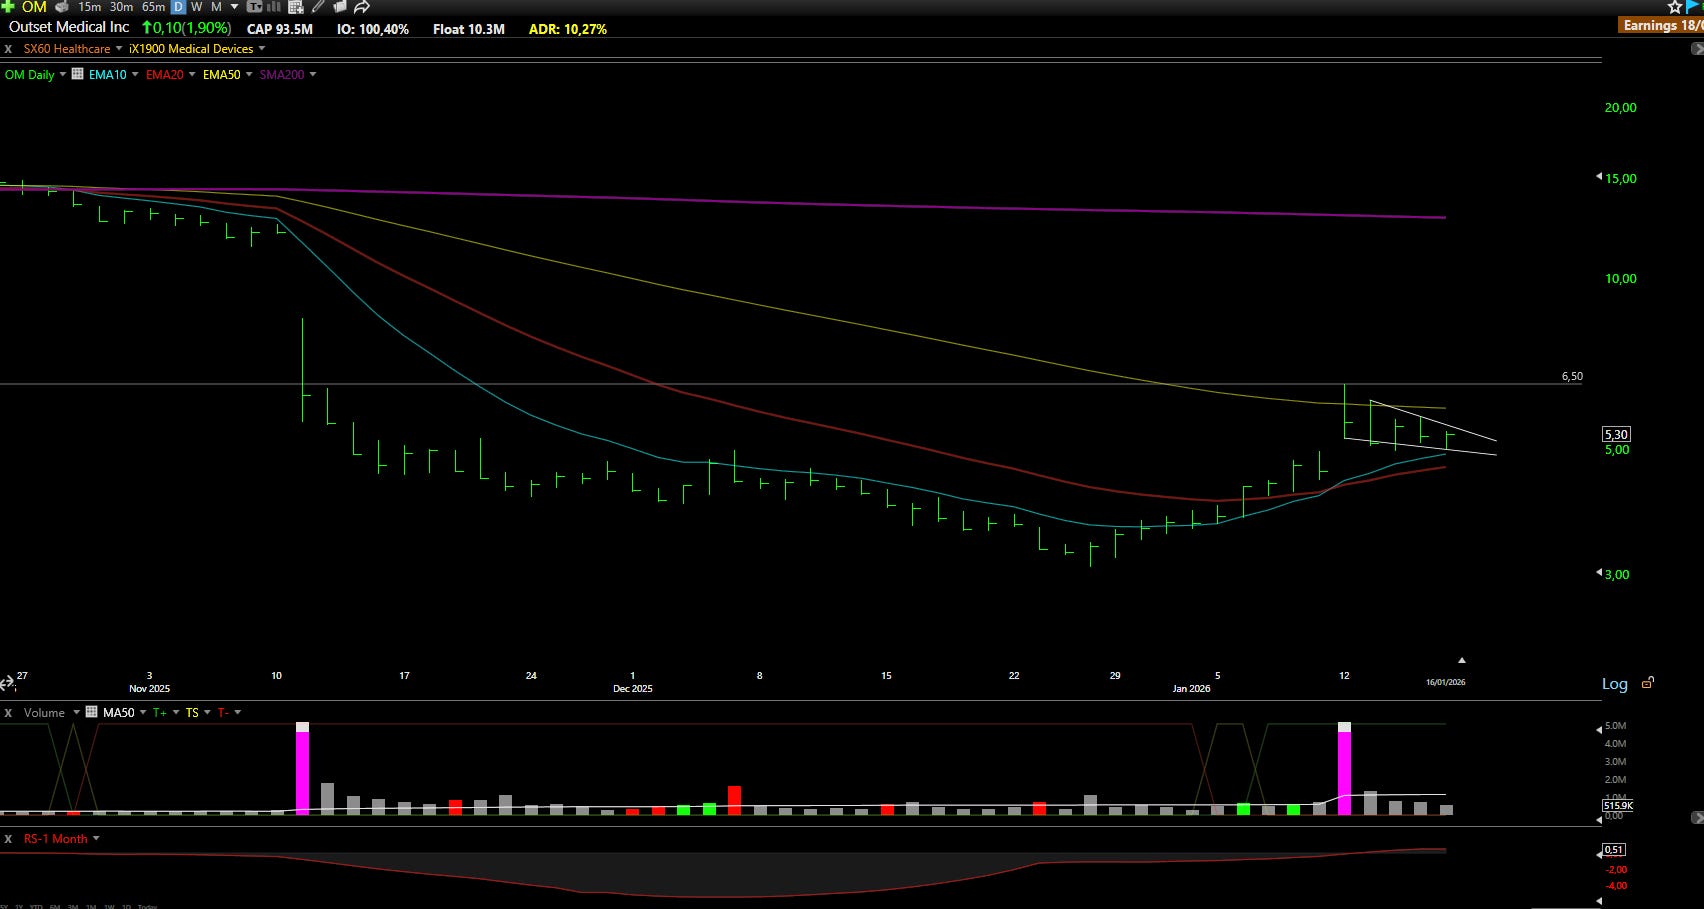
Technical Outlook: The stock made its highest volume ever since the IPO last Monday, with over 25 million shares traded, a significant event on both the daily and weekly charts. Following an initial leg up of approximately 100%, the stock is now experiencing its first pullback near key moving averages. The stock is currently trading above the 10-day and 20-day exponential moving averages, though it still needs to reclaim the 50-day EMA. Importantly, the stock is defending the $5.00 key level very well, which has become a psychological and technical support zone. The chart shows a falling wedge pattern, a typically bullish formation that often precedes a breakout to the upside. A couple of additional days of consolidation would be ideal before the next leg higher, but the stock appears to be in good shape technically for continued upside momentum.
XPOF: Xponential Fitness Inc 📊
What they do: A franchisor of boutique fitness brands
Why watch? One of the market’s primary concerns with Xponential Fitness has been the recent slowdown in same-store sales at Club Pilates, the company’s core and most recognized brand. At first glance, this deceleration appears to signal saturation or weakening demand. However, the market overlooks a key factor: Club Pilates has become one of the most well-known and largest Pilates studio brands in the world, which now allows franchisees to open new locations at nearly full capacity from day one: a stark contrast to earlier years when brand awareness was lower and ramp times were longer. This maturity actually makes same-store sales growth mathematically harder to achieve, even as the brand remains healthy. New management made the difficult but strategically sound decision to divest three lagging brands to focus exclusively on high-margin concepts: Club Pilates, StretchLab, YogaSix, and Pure Barre. This decision temporarily impacted revenue, which declined 2% year-over-year, but the quality of revenue has improved significantly as the company sheds lower-margin, capital-intensive operations. Additionally, Xponential recently secured a new loan agreement with substantially better terms, removing the risk of near-term refinancing needs while significantly reducing interest expenses. Part of the new debt will be used to buy out preferred shares, thereby eliminating the 6.5% dividend on those securities and increasing cash flow available to common equity shareholders. The company is trading at a significant discount to its peers. Looking solely at the value of Club Pilates, the stock should trade above $10.00 per share at minimum, and likely closer to $12.00, implying an easy 50% upside from current levels. As the company continues to streamline operations, reduce debt costs, and focus on its highest-quality brands, the market is likely to re-rate the stock higher.
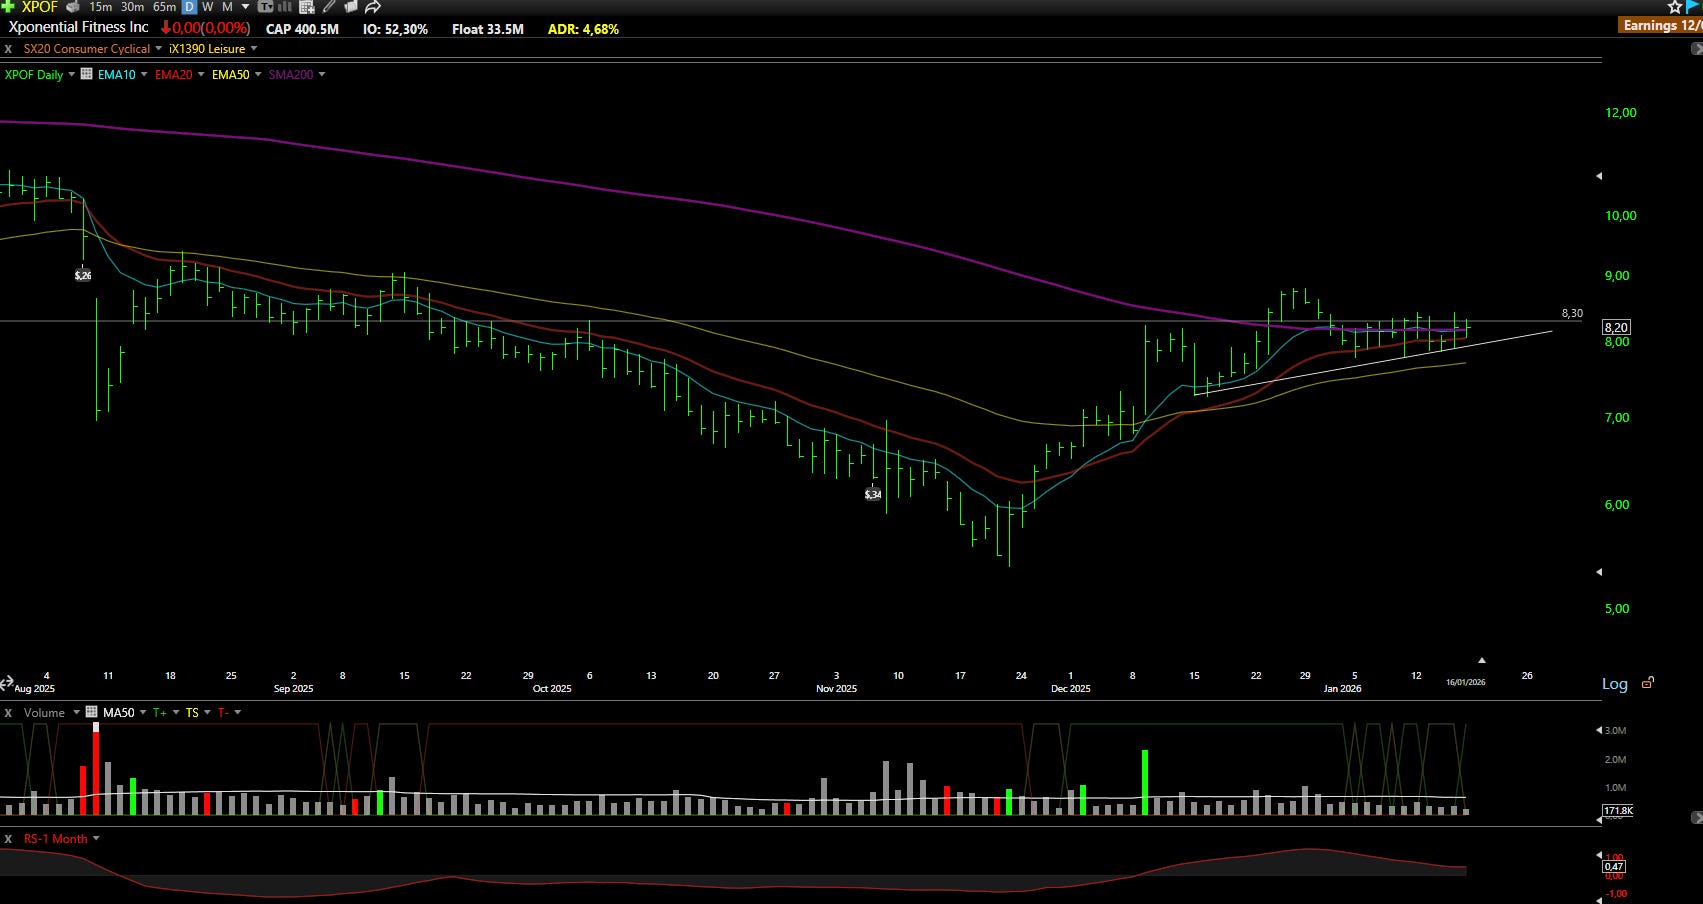
Technical Outlook: The stock is currently forming a prolonged base below the $8.30 level, creating a long handle after completing a cup-shaped pattern. All major exponential moving averages are stacked closely together and positioned above the current price, providing a clear signal of compression, a setup that often precedes a sharp move higher once resistance is broken. The key level to watch is $8.30; a decisive break above this level on strong volume would confirm the breakout and likely trigger the next leg up.
LFMD: LifeMD Inc ⚠️
What they do: A direct-to-patient telehealth company
Why watch? LifeMD is a smaller player in the highly competitive telehealth space, but it has carved out a differentiated niche by partnering with major pharmaceutical companies to offer branded GLP-1 medications: drugs like Ozempic and Wegovy that have become blockbuster treatments for weight loss and diabetes. Unlike many competitors who have relied on compounded (off-brand) versions of these drugs with questionable regulatory standing, LifeMD strategically partnered with both Eli Lilly and Novo Nordisk to offer their branded GLP-1s directly through its platform. This above-board approach reduces regulatory risk and positions LifeMD as a trusted distribution channel as demand for these medications continues to surge. For the first nine months of 2025, compared to the same period in 2024, telehealth revenue is up 34%, and adjusted EBITDA is up 294% as the company surpasses its fixed costs and moves toward profitability in a low marginal cost, capital-light business model. Telehealth is undeniably a competitive landscape with limited moats, but LifeMD’s partnership with Medifast (which provides access to tens of thousands of health coaches and personal trainers who can refer clients to LifeMD for GLP-1 prescriptions) is a significant distribution advantage. Additionally, LifeMD recently divested its SaaS subsidiary WorkSimpli for a valuation of $65 million, a remarkable outcome considering the company acquired 51% of WorkSimpli for just $250,000 in 2018. The proceeds were used to pay off all $17 million of LifeMD’s debt, leaving the company with a fortress balance sheet at exactly the moment volumes are ramping and the company is approaching GAAP net income profitability. This is a compelling play on GLP-1 tailwinds with improving unit economics and a clean capital structure.
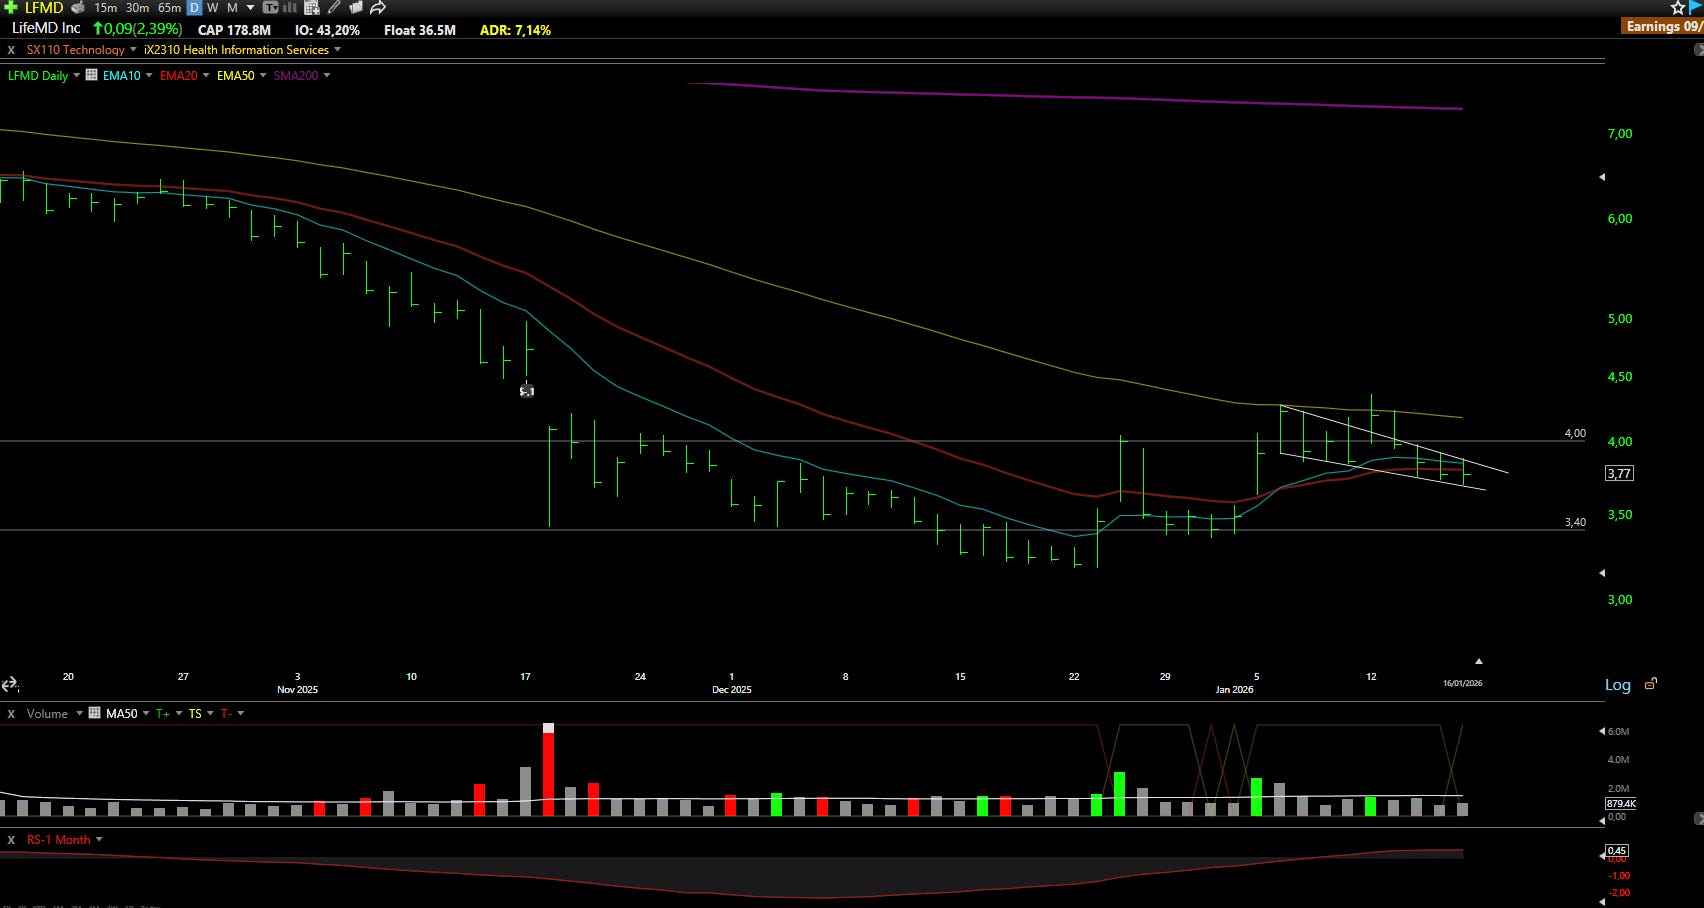
Technical Outlook: The stock is currently trading near the 10-day and 20-day exponential moving averages. Next week will be critical to determine whether these moving averages will provide support or whether the stock needs another pullback to the $3.40 key weekly support level. The stock appears to be forming a large saucer-with-handle pattern, though it remains quite volatile. The real level to watch for confirmation is $4.00, a recent major resistance level that the stock needs to break decisively in order to establish a healthy uptrend. If you prefer not to anticipate the breakout, waiting for a move above $4.00 on volume would provide a cleaner entry.
SND: Smart Sand Inc ⚠️
What they do: A supplier of frac sand and related logistics services to the oil and gas industry
Why watch? Smart Sand reported record third-quarter 2025 results, secured a new supply deal with EQT (one of the largest natural gas producers in the U.S.), guided full-year volumes above expectations, maintained a strong balance sheet, and recently announced another special dividend, demonstrating disciplined capital allocation and shareholder-friendly management. The company specializes in Northern White sand, a premium-grade proppant favored for its strength and consistency, and has built one of the most extensive sand logistics networks in North America, capable of delivering sand efficiently and cost-effectively to all major shale operating basins. Smart Sand’s commitment to opening new markets for its high-quality sand continues to deliver results. In the third quarter, the company achieved record sales volumes in Canada, broadened its customer base in Industrial Product Solutions (non-energy applications of sand), and expanded its presence in the Utica shale through its Ohio terminals. Additionally, the company saw strong sand sales in its traditional markets of the Marcellus and Bakken shales. Despite short-term volatility in oil and natural gas prices, management continues to see consistent activity in the primary markets it serves. Importantly, the company believes the long-term fundamentals for natural gas are strong, driven by increasing LNG export capacity in both the United States and Canada, as well as the continued need for increased electric power to support growing AI data center demand. Smart Sand is well-positioned to capitalize on this structural demand growth, supported by one of the largest reserve bases of fine mesh Northern White sand in North America and a logistics network that provides a durable competitive advantage. The company’s excellent capital allocation (returning cash to shareholders through special dividends while maintaining a clean balance sheet) further enhances its appeal as a disciplined operator in a cyclical industry.
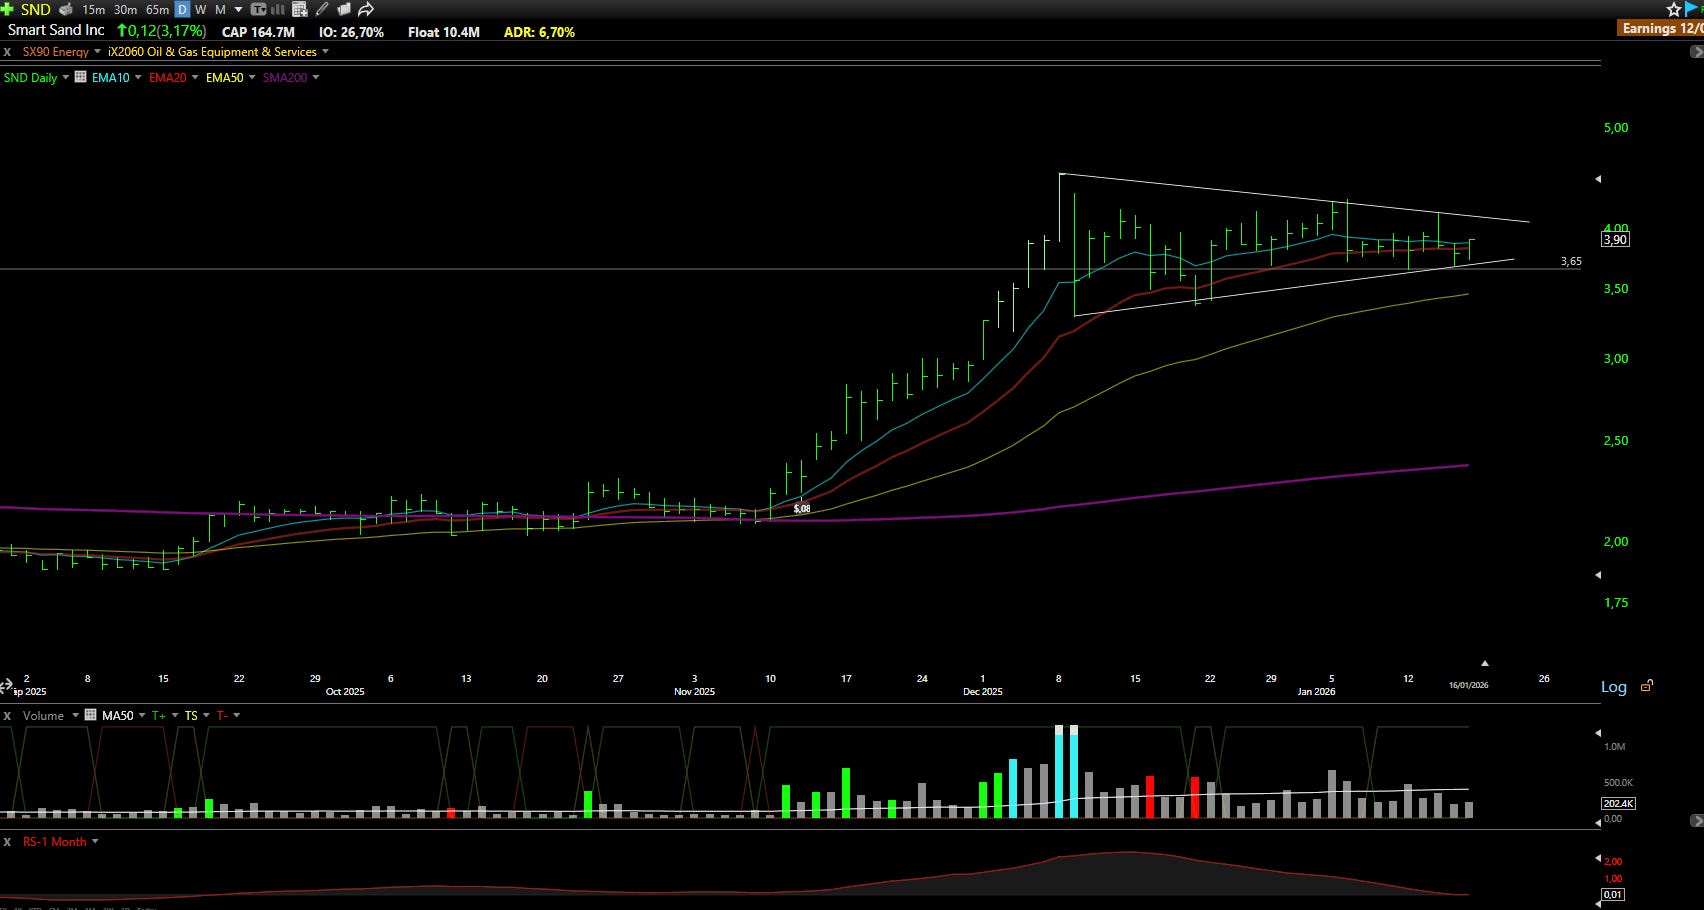
Technical Outlook: The stock has consolidated for nearly a month, which is constructive, though it likely needs at least another week or so of base-building before the next move. Key support sits at $3.65, and after the initial strong leg up, the stock is now flagging nicely. This is definitely a stock to watch in the near future, particularly if natural gas prices stabilize or move higher.
SVRA: Savara Inc 📊
What they do: A biopharmaceutical company focused on developing therapies for rare respiratory diseases
Why watch? Savara is on the cusp of potential FDA approval for molgramostim (also called Molgradex or MOLBREEVI), an inhaled biologic therapy for autoimmune pulmonary alveolar proteinosis: an ultra-rare lung disease where the body produces antibodies that attack GM-CSF, a protein critical for clearing surfactant from the lungs. This leads to a buildup of material in the alveoli (the tiny air sacs in the lungs), causing patients to be chronically short of breath. Current U.S. diagnosed prevalence is estimated at around 5,500 patients, making this a classic orphan drug opportunity with significant pricing power. The current standard of care is whole lung lavage under general anesthesia: a procedure where doctors literally wash out the lungs with saline. It’s invasive, temporary, and not a true treatment. Some major pulmonary centers use off-label inhaled Leukine (sargramostim), an injectable drug approved for a different indication that hospitals are converting into an inhaled form on their own; a practice that is neither standardized nor FDA-approved. What Savara is doing is developing a dedicated inhaled formulation from the ground up, packaged with the eFlow nebulizer (an electronic device that delivers precise doses), and seeking approval for this integrated product. In practice, this means selling a standardized, electronic dosing system that locks in the dose and regimen specifically for aPAP, a significant improvement over current off-label use. The company resubmitted its Biologics License Application (BLA) in December 2025 after addressing previous chemistry, manufacturing, and controls (CMC) issues that led to an earlier rejection. The timeline is now: BLA approval expected in February 2026, U.S. PDUFA (FDA decision date) in August 2026, and European PDUFA in Q1 2027. Clinical data have been robust, with over a year of treatment showing no serious adverse events. As long as the company doesn’t repeat its previous CMC mistakes (and it’s rare to see a company fail CMC twice), approval odds are high. Combined U.S. and Europe analyst target prices sit around $10.00-11.00, with pricing assumptions of approximately $400,000 per patient annually. With a small patient population, high unmet need, and no approved competition, Savara represents a classic binary biotech opportunity with significant upside if approval is granted.
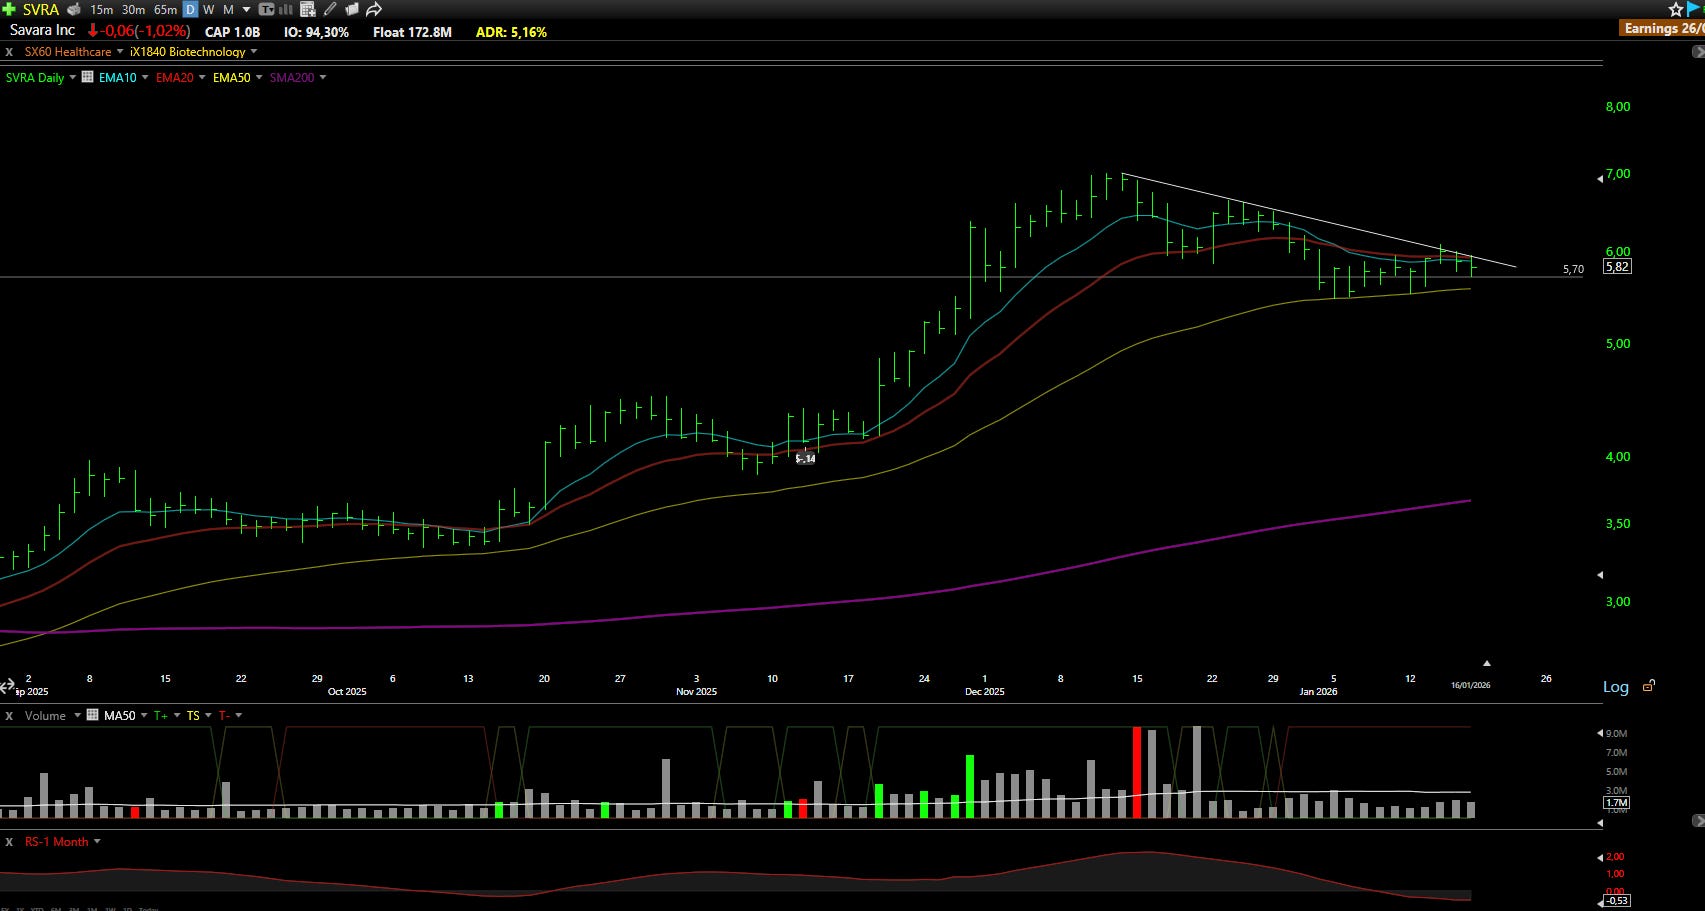
Technical Outlook: The stock has bounced twice off the 50-day exponential moving average, and $5.70 has emerged as a key support level to watch: currently very close to the current price, providing an attractive risk-reward setup. The ideal scenario is a bit more compression over the next couple of days, followed by a convincing break to the upside on higher volume. Given the proximity to support, this offers a well-defined entry point with limited downside risk if the setup fails.
BULL: Webull Corporation 📊
What they do: A digital brokerage platform offering commission-free trading in stocks, options, ETFs, and cryptocurrencies
Why watch? Webull is now trading at a 5x trailing-twelve-month sales multiple following another dip in its share price, even as its fundamentals show rapid improvement. The company posted over 50% year-over-year revenue growth, a 15% operating profit margin, and record net deposits and customer assets in the third quarter. Webull generates revenue through back-end streams, including margin interest, payment for order flow, interest on free credit balances, and stock lending: a diversified model that benefits from higher trading volumes and rising interest rates. Looking ahead to 2026, trading volume is expected to remain elevated or increase further, bringing more revenue growth. Webull is trading at a multiple markedly lower than its peer Robinhood, which trades at 20x sales. Fundamentally, there are stronger companies in the sector, but technically, the opportunity appears compelling.
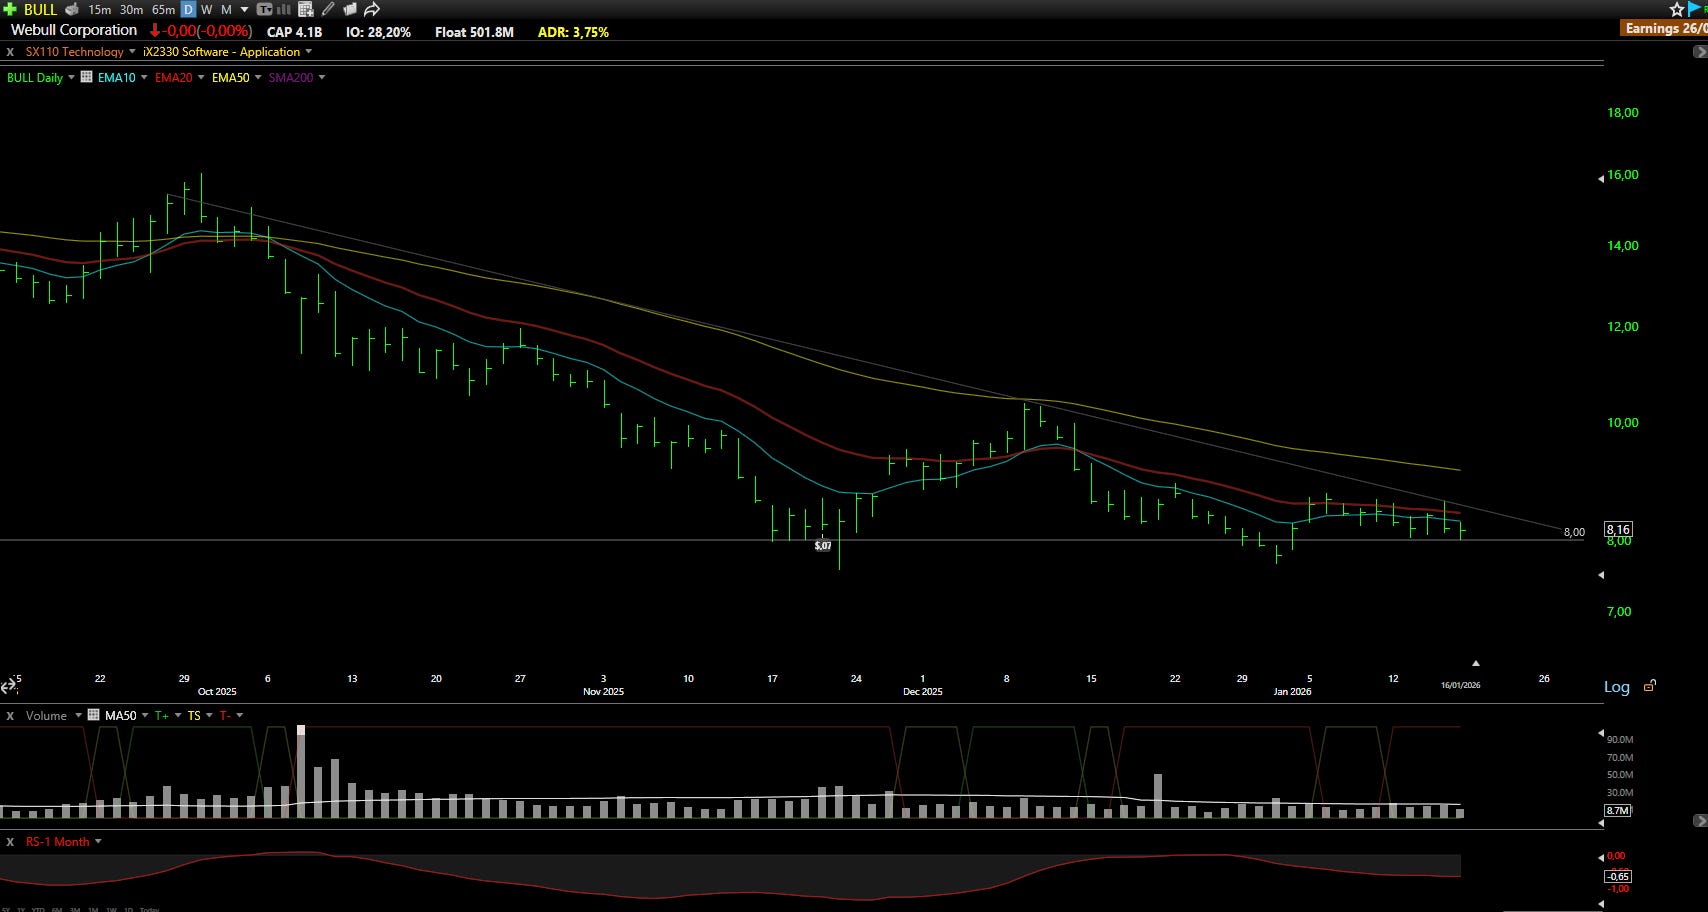
Technical Outlook: On both the weekly and daily charts, the $8.00 level has emerged as a key support zone, defended successfully nearly three times, most recently last week, and initially in November. There is also a clear weekly downtrend line from October 2025 that represents the level to watch for an explosive breakout. The preferred approach is to enter in anticipation using the $8.00 level as real support, betting that the stock will avoid dipping below it again. The stock has already experienced a significant decline in share value, and a bounce or upside move appears increasingly likely. Additionally, the crypto and stablecoin theme could provide a tailwind for stocks like Webull, driving renewed interest and buying pressure. Of course, the general market must cooperate, or the setup will be invalidated. This is a speculative play at the moment, but one with clearly defined risk and potential for outsized reward if the technical setup resolves to the upside.
These tickers below didn’t make the main cut, but they’re on our radar for a reason. We’ve vetted them; now you decide if they fit your game.
More opportunities, less noise.
⚡📋Scanned Stocks: Quick Picks
EKSO - Ekso Bionics Holdings Inc
CMTL - Comtech Telecommun Corp
STTK - Shattuck Labs Inc
PPIH - Perma-Pipe International Holdings Inc
USAR - USA Rare Earth Inc
"As a general rule of thumb, the more complexity in a Wall Street creation, the faster and further investors should run."
David Swensen
Disclaimer: This analysis is for informational purposes only and should not be considered financial advice. Always conduct your research and consult with a licensed financial advisor before making investment decisions.