

The Art of the Wait (And Why You’re Going to Die Anyway)
Let’s be honest about what happened this week. The noise (whatever the hell the headlines were screaming about) faded into the background. The panic sellers wiped the vomit off their chins, looked at the screens, and decided maybe the world wasn’t ending after all.
Stocks clawed back, recouping the losses, and everyone patted themselves on the back.
But don’t get comfortable.
Here’s the thing they won’t tell you on CNBC while they’re flashing green arrows and smiling like sharks: The machine wasn’t built for you. It was built to grind you down, to extract your capital and your sanity in equal measure. We are in a volatility grinder now. The easy money? That’s gone. Now we’re in the trenches, and the only thing that matters is survival.
You see it all the time. Good operators are getting chewed up not by the market, but by their own wiring. Fear when the floor drops out. Euphoria when the line goes up. Anxiety when the P&L flatlines. It’s an emotional whirlpool, and if you let it, it will pull you under.
We have to look back to the old guard. I’m not talking about Buffett or Soros. I’m talking about Marcus Aurelius. The Stoics. These guys understood that the world is chaotic.
“You have power over your mind, not outside events. Realize this, and you will find strength.”
That’s the trade. Right there. You can’t control the Fed. You can’t control the algo-sweeps. You can’t control whether the market decides to rip your face off at the open. The only thing you control is your process. The only thing you control is how you take the punch.
But let’s go deeper.
Memento Mori.
Remember that you will die.
I want you to really sit with that. It sounds morbid, I know. But in this game, it is the ultimate liberation. When the screen is bleeding red, when your thesis is crumbling, when you feel like absolute sh*t because you missed the move or took the loss, remember that you are dust.
We have one life. Just one. And it is terrifyingly short. Do you really want to spend your limited time on this spinning rock, letting a fluctuating number on a glowing screen dictate your self-worth?
Trading is what we do. It is the craft. We love the action, the puzzle, the fight.
But it is not who we are.
If you let the outcome of a trade bleed into your dinner with your family, or ruin the taste of a good bottle of wine, the market has already beaten you.
Put it in perspective. You are going to die. The market will be here long after you’re gone, blinking and flashing for the next generation of suckers.
So relax. Take a breath. Detach.
Now, let’s look at the board.
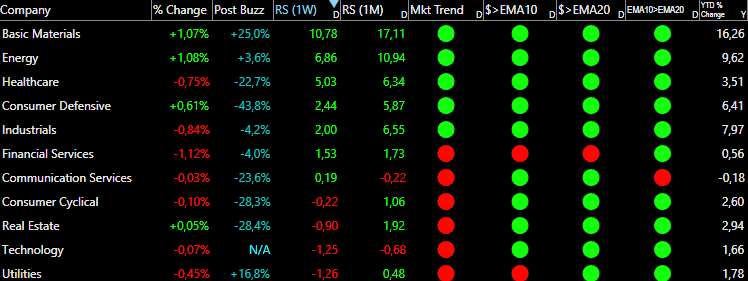
We started this intro with philosophy because, frankly, the tape this week was a mess.
We opened a position, but for the most part? We stayed flat. We sat on our hands.
Friday was a masterclass in illusion. You saw the heavy lifting.
The “Big Boys” (Netflix, Microsoft, the generals of this army) held the line. They dragged the indices higher. That’s important. It keeps the dream alive for next week. But look under the hood.
Our watchlist is thin. We are scanning thousands of charts, looking for that perfect setup, that moment where the probability tilts in our favor, and we’re coming up empty. It’s harder and harder to find good names.
So, what do we do? We wait.
Earnings season is coming down the pipe like a freight train, and that’s going to be the next key pivot.
Until then, pour a drink. Hug your kids. Remember Memento Mori. And be ready to react when the bell rings.

Latest articles:


Each stock carries a risk badge: ⚠️ High | 📊 Medium | 🛡️ Low.
Based on volatility, float, technicals, and fundamentals. Size your positions accordingly.
📈 Free Setup: Make It Count
EAT: Brinker International Inc🛡️
What they do: A restaurant operator managing casual dining brands
Why watch? Brinker has executed an exceptional turnaround of its Chili’s brand, making it one of the top-performing restaurant concepts in the industry over the past two years. However, concerns about the sustainability of restaurant spending and margin pressure due to ongoing consumer affordability challenges have weighed on the sector and EAT shares. The challenge is clear: consumers are pulling back and becoming more selective with discretionary spending. Restaurants have partially offset declining traffic by raising prices, but this strategy has limits. One positive development is that restaurant input costs appear to be easing. Higher beef prices have been a particular source of margin pressure, but we believe the worst is behind us. The Administration’s elimination of tariffs on Brazilian beef and increased imports from Argentina should expand supply and alleviate pricing pressure. While Chili’s is performing exceptionally well, the Maggiano’s brand is in the early stages of its own turnaround, implementing a playbook similar to what succeeded at Chili’s, including a revamped menu refocused on classic dishes, investments in improved service, and restaurant refurbishments. Brinker generated $72 million of free cash flow, even with $47 million in seasonal working capital headwinds. Importantly, the company maintains a strong balance sheet with just $526 million in long-term debt and finance leases, translating to less than 1x debt-to-EBITDA leverage.
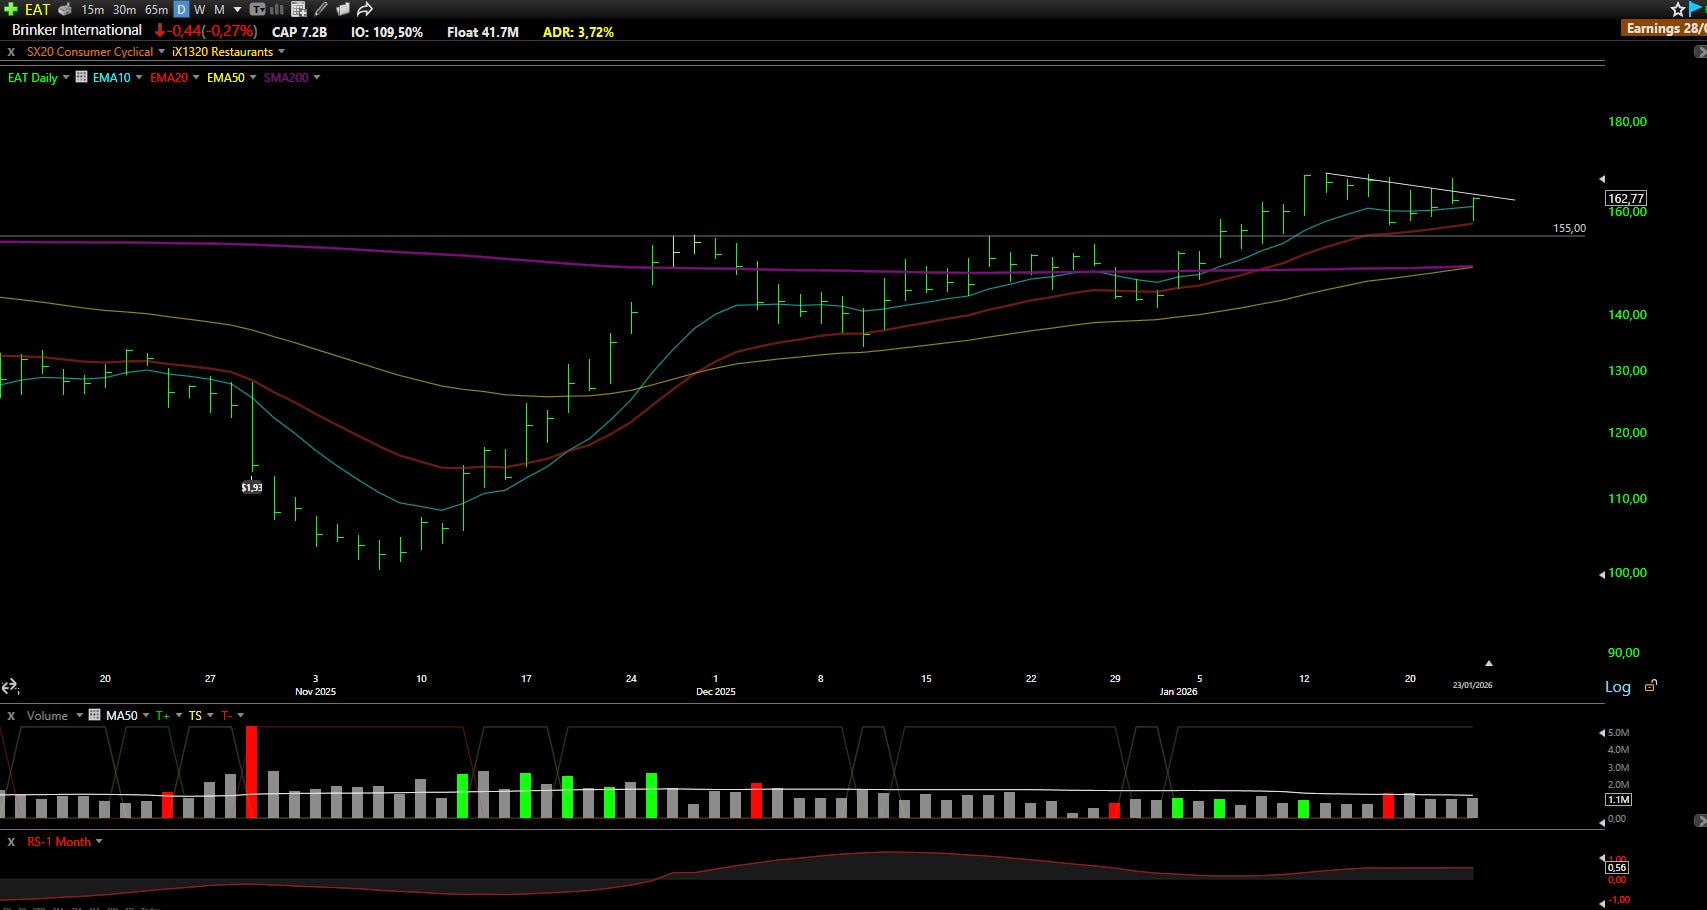
Technical Outlook: The stock has already delivered an impressive 60% gain from its recent bottom. After breaking above the $155.00 level (a move we unfortunately missed), the stock tested this same level last week and found support at the 10-day exponential moving average, now forming a tight flag pattern. With a stop-loss positioned below the 20-day exponential moving average, the stock offers an attractive risk-reward setup in a beaten-down sector, and EAT appears to be the clear leader. If the consolidation resolves to the upside, the next leg higher could be significant.
Why We Don’t Wait for Sunday
Markets don’t move on your schedule. The best low-risk entries don’t announce themselves politely and wait for the weekend newsletter.
They show up when they show up. And if you’re not positioned, you miss them.
Paid members get real-time alerts: exact entries, stops, position sizing, and the thesis behind every trade. The same information we use to manage our own capital.
Free members get just one pick on Sunday.
Does that sound like an edge to you?
What’s Inside Premium
📊 Watchlist Elite (7-9 Stocks)
Each selection undergoes rigorous financial analysis, technical evaluation, and strategic assessment.
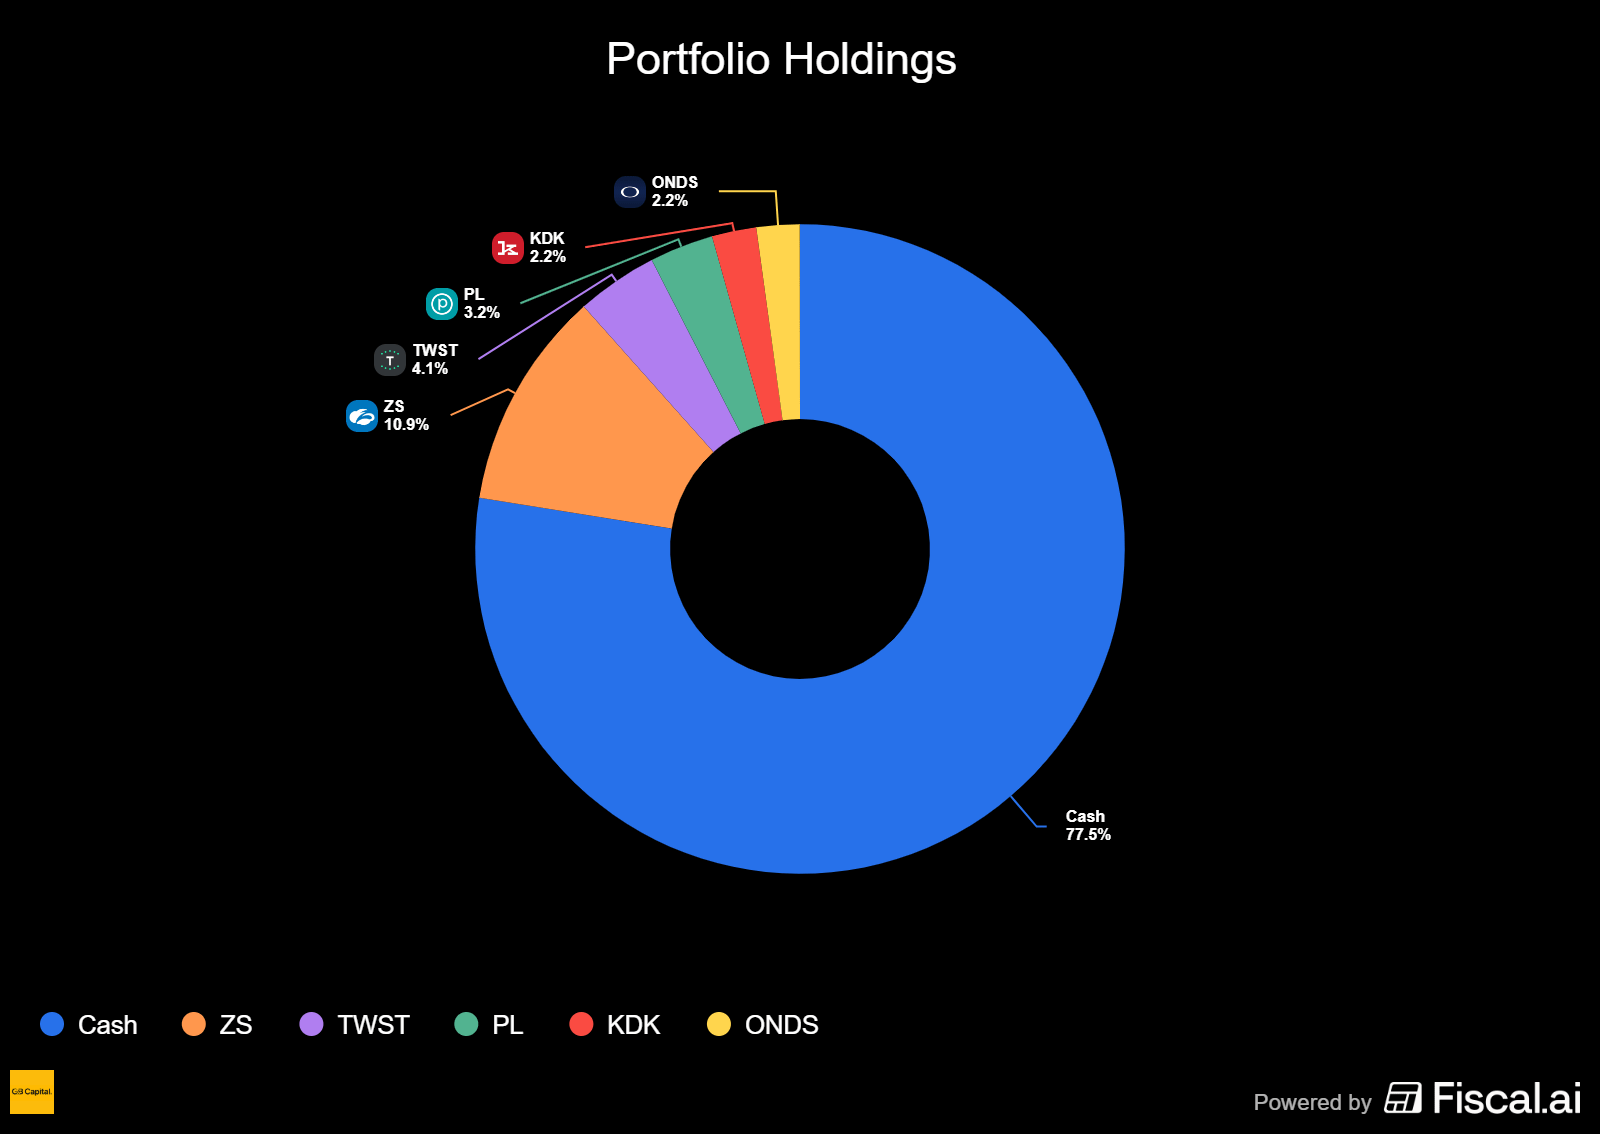
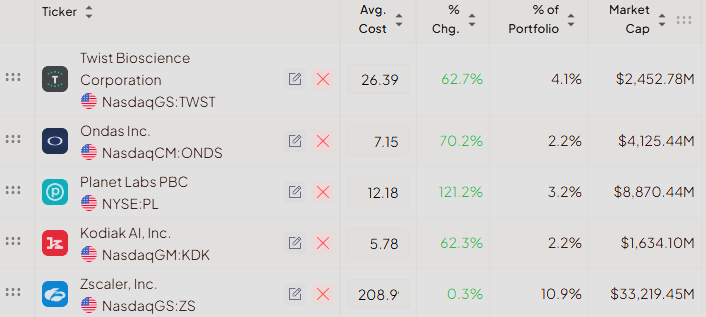
💼 Full Portfolio Transparency
Every position we hold. Entry price. Current P&L. Stop level. Real money, real risk.
⚡ Real-Time Trade Alerts (Chat Access)
This is where the edge lives. Exact entries, stops, and position sizing. Real-time. No lag
🎯 Quick Picks (5 Names)
Additional setups that just missed our main criteria but are worth watching.
💬 Chat Access
See our thought process in real time. Ask questions. Watch how we manage risk.
🛠️ The Tools We Actually Use
Member discounts on TC2000, Fiscal.ai, and other platforms. Same tools, better pricing.
What Paid Members Say:
We’re entrepreneurs first, traders second. We’ve sat in the CEO chair. We know what real execution looks like and how to spot it.
€39/month or 299€/year. Less than one losing trade. Cancel anytime.
Portfolio updates and new positions:

⚡ AI-optimized, human-verified: Our expert team carefully selected Premium market intelligence from Fiscal.ai data. Explore now →
💎📈 Watchlist Elite: Premium Market Movers
CMTL: Comtech Telecommunications Corp ⚠️
What they do: A defense technology company specializing in advanced satellite communications systems
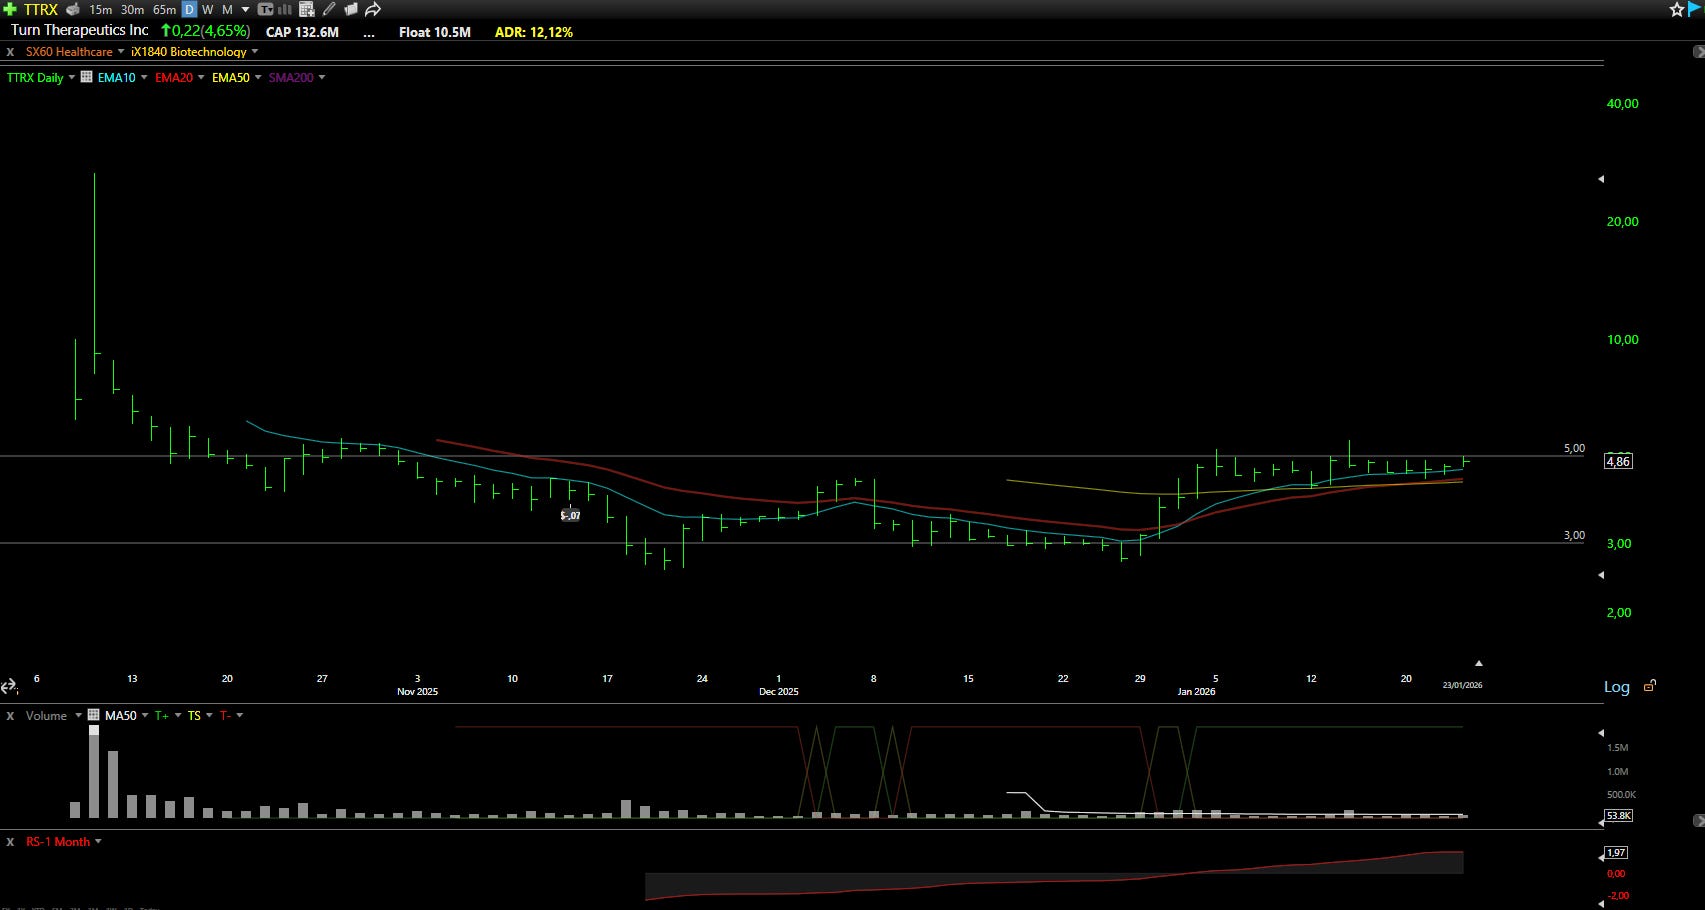
Why watch? The market appears to be significantly undervaluing Comtech Telecommunications at its current $150 million market capitalization. Our analysis suggests the company’s restructured Space & Satellite division alone could be worth approximately $500 million. Throughout 2025, Comtech underwent a comprehensive transformation, including facility consolidation, leadership changes, and strategic portfolio optimization focused on higher-margin defense products. The company’s flagship COMET troposcatter system represents a breakthrough in battlefield communications: it’s the world’s most compact and portable over-the-horizon platform, capable of deployment in just 15 minutes compared to hours for competing systems. With an operational range exceeding 25 miles and enhanced performance in adverse weather conditions (unlike satellite or other alternatives), COMET has proven itself in real combat environments. In March 2025, Comtech secured $26 million in sole-source follow-on contracts from L3Harris for the Anti-Jam Modem (A3M) program, which provides software-defined, anti-jamming capabilities for U.S. satellite communications and tactical satellite networks. Perhaps the most overlooked catalyst is Comtech’s position as a qualified supplier for Amazon’s Project LEO ground station gateways (formerly Project Kuiper), which has entered an accelerated deployment phase. Industry speculation about Comtech’s involvement dates back to 2020, but the market has largely ignored this potential revenue stream as the project scales commercially.
Technical Outlook: CMTL has been consolidating in a tight range between $5.00 and $6.00 since late December, forming what technical analysts call a Darvas box pattern. The stock has recently found support at both the 10-day and 20-day exponential moving averages, which are trending upward: a positive sign of accumulation. The $6.00 level is clearly the critical resistance to watch, representing a significant technical barrier on both daily and weekly charts. A breakout above this level on strong volume could trigger the next leg higher and potentially begin to close the valuation gap between the current market cap and the underlying asset value.
TTRX: Turn Therapeutics ⚠️
What they do: A clinical-stage biopharmaceutical company developing innovative dermatology treatments
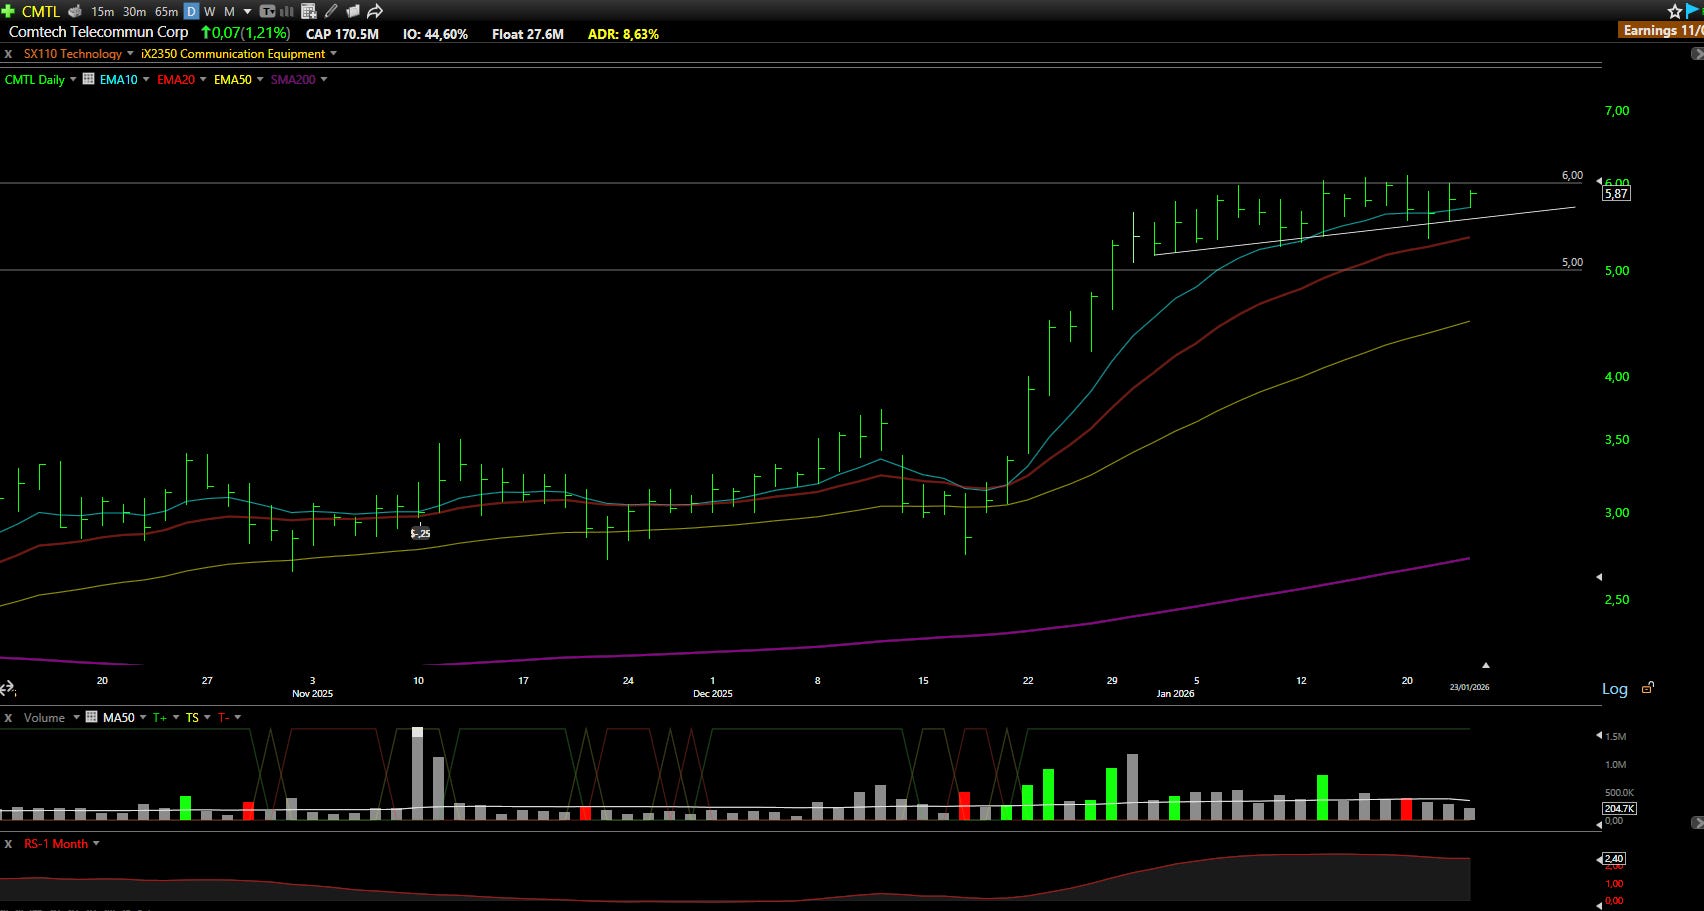
Why watch? Why watch? Turn Therapeutics recently achieved significant industry recognition when Patient Care Online Magazine named its lead candidate among the “Five Novel Mechanisms Reshaping Atopic Dermatitis Treatment.” This distinction places TTRX alongside a select group of innovators redefining eczema therapy and represents meaningful validation from a trusted clinical news source with substantial influence among dermatologists, nurse practitioners, and frontline physicians. For an early-stage biotech company, this visibility boost could prove transformative in attracting both clinical partnerships and investor attention. The company is advancing its FDA-cleared Hexagen formulation into new indications, including eczema and onychomycosis (nail fungus). If the lead candidate GX-03 succeeds in clinical trials (particularly given its localized delivery advantage targeting unmet medical needs), the massive eczema market could drive substantial stock appreciation. Additionally, Turn Therapeutics has secured a global distribution agreement with Medline, which could serve as a major commercial catalyst if products advance to market. Insider activity has been notably positive, with company insiders purchasing shares in October, November, and December 2025 in the $3.00-$4.00 range, not far from current trading levels: a strong signal of internal confidence.
Technical Outlook: The stock has been consolidating constructively throughout January, holding above all key moving averages and approaching the critical $5.00 resistance level. This consolidation pattern suggests accumulation and base-building after the recent IPO volatility. A breakout above $5.00 on elevated volume could trigger a measured move targeting the $8.00-$8.50 range based on the width of the current consolidation pattern. The technical setup appears favorable for patient investors willing to wait for confirmation of the breakout.

Put the market on autopilot, experience the Best Platform with TC2000
Explore now →
TSSI: TSS, Inc ⚠️
What they do: A specialized systems integrator focused on AI rack integration and data center infrastructure
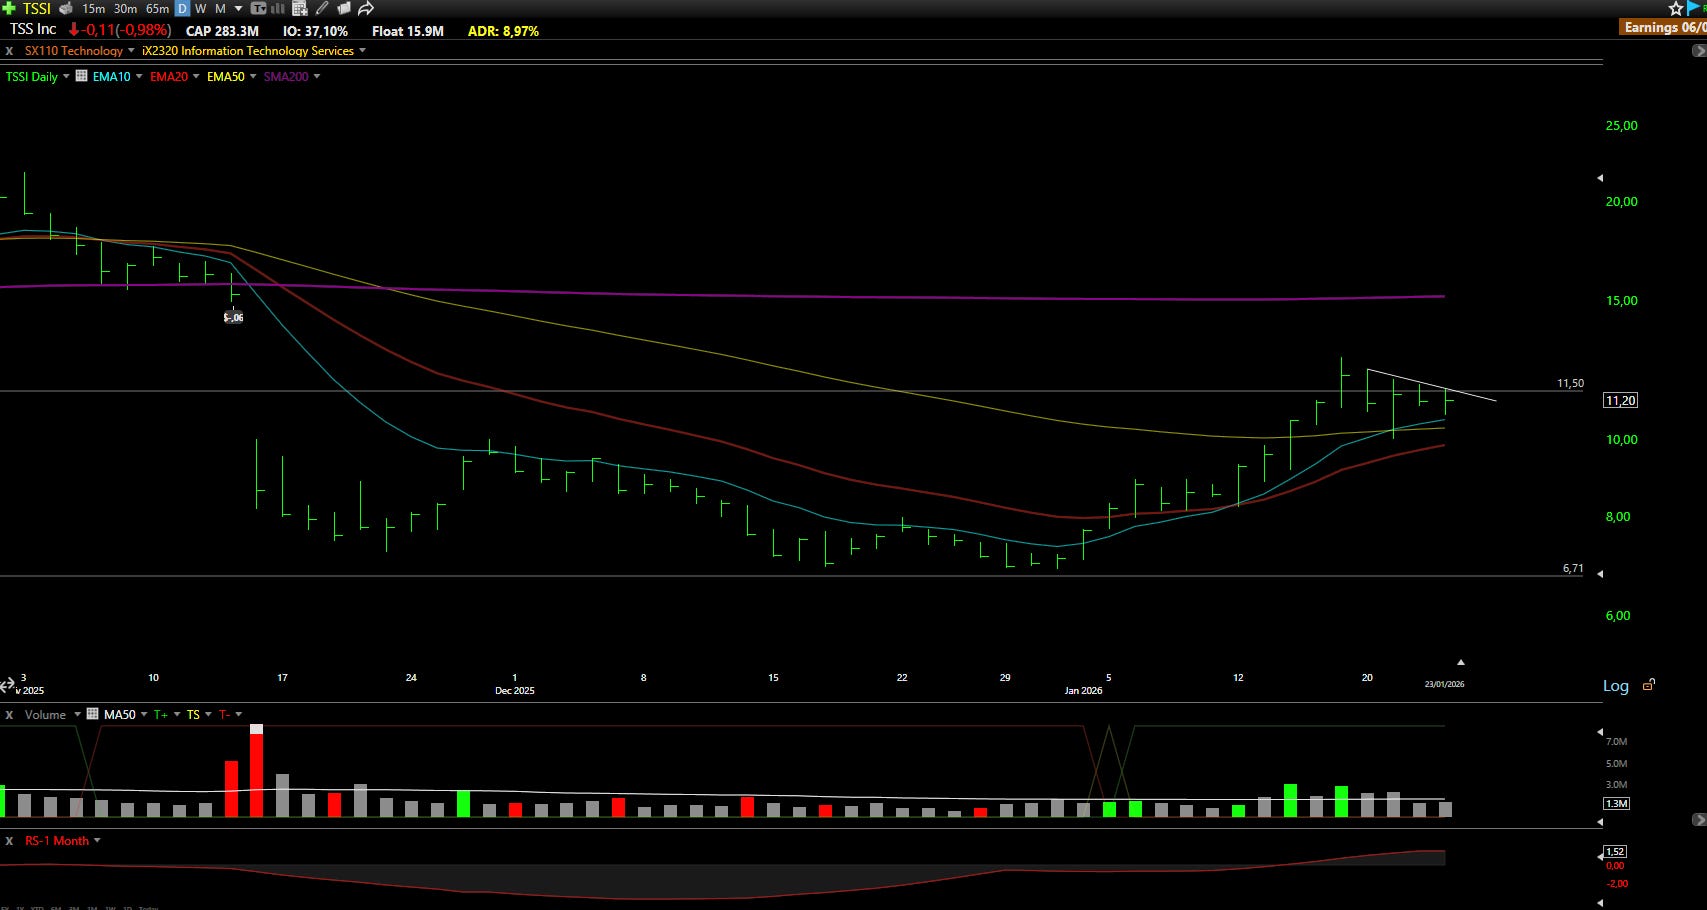
Why watch? TSS signed a five-year agreement with Dell supporting expansion into the rapidly growing AI infrastructure market. The company’s revenue mix includes lower-margin equipment procurement, higher-margin AI integration services, and a declining facilities management segment. While Q3 earnings disappointed investors and raised questions about management execution, the company has provided guidance suggesting significant EBITDA and net income growth heading into fiscal year 2026. Management attributes recent challenges to temporary operational issues related to ramping up its expanded Georgetown facility, which they claim have been resolved. Despite concentration risk around Dell and potential M&A uncertainties, TSSI’s expanded infrastructure capacity and confirmed operational improvements offer recovery potential if execution improves. Importantly, the data center theme is gaining momentum among investors: stocks like IREN surged on Friday, signaling this could emerge as the next major investment theme if the broader market maintains its bullish trajectory.
Technical Outlook: The stock tested the 50-day exponential moving average last week and found clear support, demonstrating underlying demand. The key support level to monitor is $10.00, which previously acted as resistance and has now flipped to support, a bullish technical development. The stock must hold above this level for the investment thesis to remain valid. After forming what appears to be a large cup pattern, TSSI is now working on the handle portion of a potential cup-and-handle formation. The line in the sand is $11.50: a breakout above this level would complete the pattern and could trigger the next upward move. We’re tracking multiple names with similar setups as the data center theme proliferates across the market.
HOVR: New Horizon Aircraft Ltd ⚠️
What they do: A Canadian aerospace innovator developing hybrid electric vertical takeoff and landing (eVTOL) aircraft
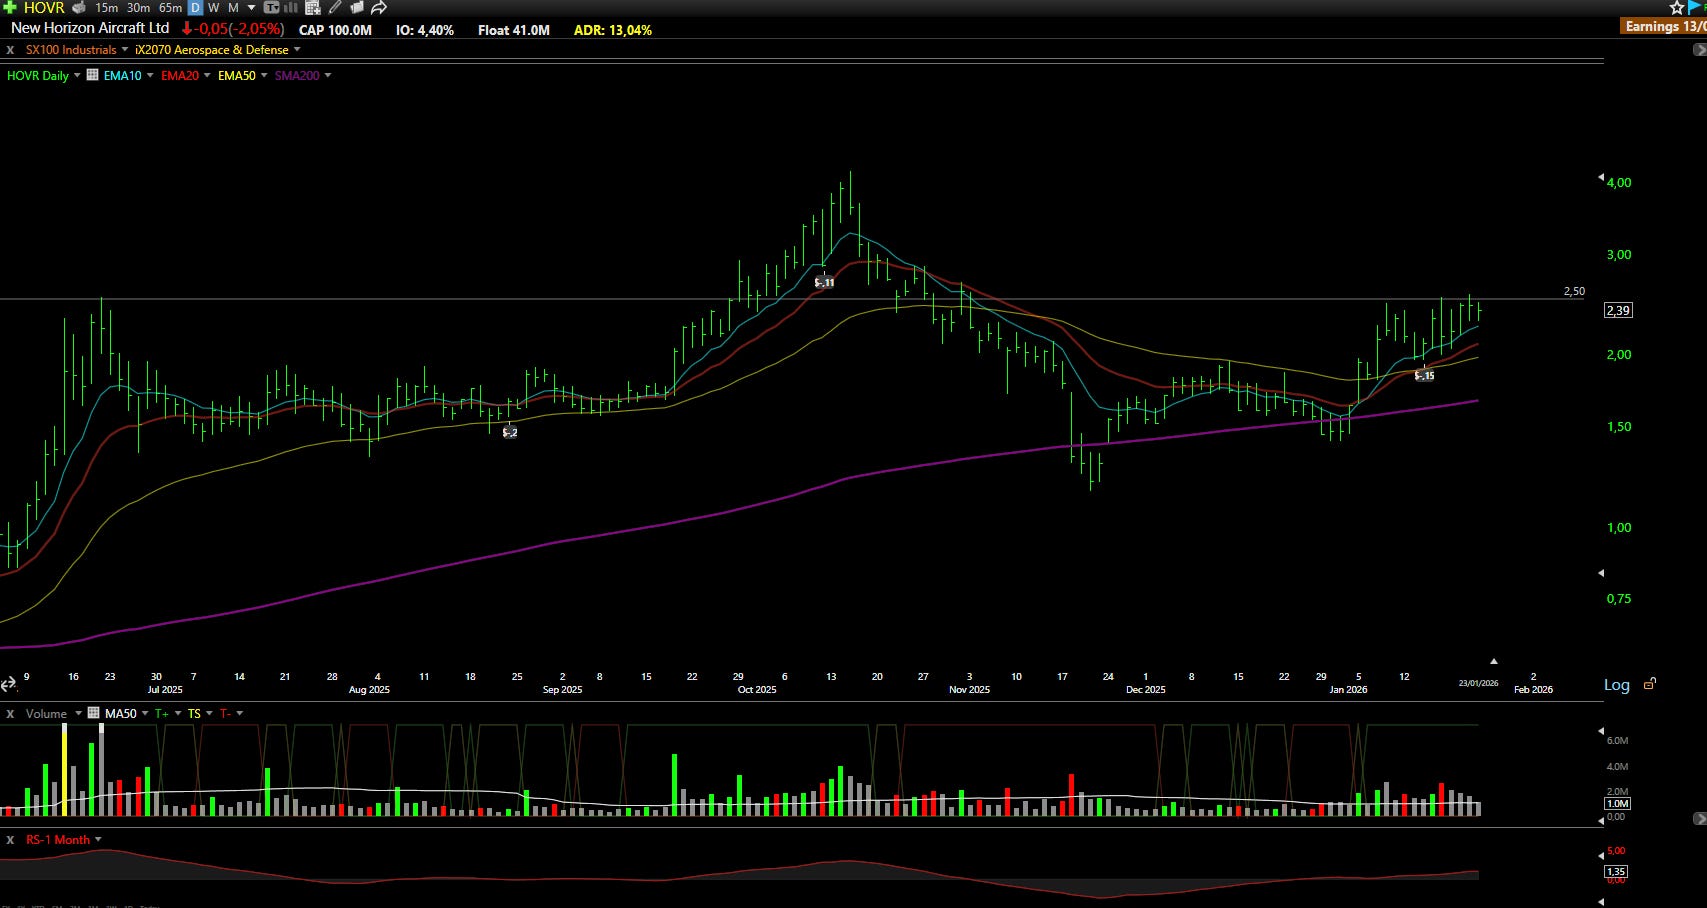
Why watch? New Horizon Aircraft represents one of the most compelling opportunities in the emerging eVTOL sector. The Toronto-based company initially focused on military applications, evolving from general aviation modifications to advanced eVTOL systems designed to address the limitations of traditional helicopters, offering faster speeds, lower operating costs, and greater durability. In May 2025, the company achieved a major milestone when its large-scale prototype completed the world’s first fan-in-wing transition flight. The aircraft utilizes a patented fan-in-wing system where lift fans are embedded inside the wings and revealed only during takeoff and landing; once airborne, the wings close and the aircraft flies like a conventional airplane, dramatically reducing energy consumption and enhancing safety. The full-scale prototype is scheduled for completion in late 2026, with flight testing beginning in early 2027. The company is pursuing certification from both the FAA and Transport Canada. The Cavorite X7 uses a Pratt & Whitney PT-6A turbine engine combined with electric subsystems, reducing battery dependence and enabling operations in challenging weather conditions, one of the primary obstacles facing fully electric eVTOL competitors. The aircraft operates 98% of flight time in conventional airplane mode, activating the fans only for vertical takeoff and landing. New Horizon estimates the cost per passenger mile at $1.93, compared to $4.64 for a Bell 429 helicopter, representing a 58-64% cost reduction along with nearly 90% faster speeds. A critical differentiator is the potential for “Flight Into Known Icing” certification, which would permit operations in adverse weather: a prerequisite for viable commercial service in regions like Canada and Northern Europe.
Technical Outlook: HOVR is demonstrating notable relative strength compared to sector peers (JOBY and ACHR have weaker chart patterns). The stock has been printing higher lows since early January and is now approaching the $2.50 level, a critical resistance that has been tested approximately three times this month, with each attempt rejected. The 10-day exponential moving average is the key indicator to monitor, as it has been providing consistent support. As long as the price remains above this moving average, the technical posture remains bullish and suggests accumulation ahead of a potential breakout.
SNBR: Sleep Number Corporation ⚠️
What they do: A specialty sleep retailer that designs, manufactures, and sells premium adjustable air mattresses
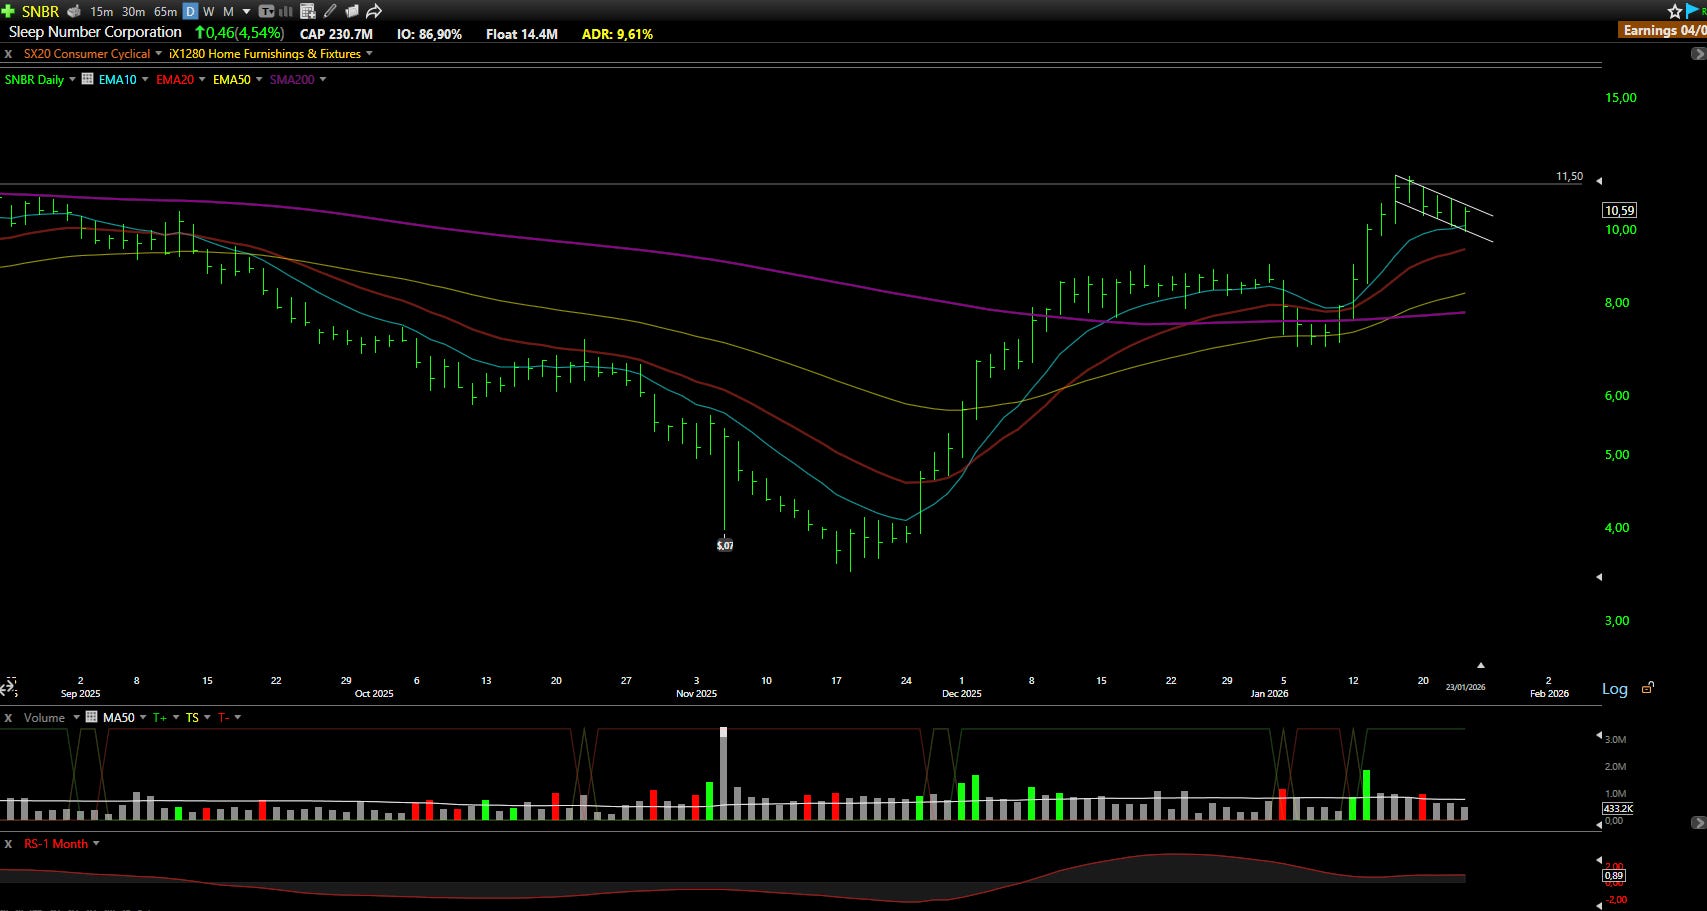
Why watch? Sleep Number is navigating a challenging consumer spending environment as new management executes an aggressive cost-cutting program while attempting to reignite growth. The company is repositioning its product lineup to appeal to a broader range of cost-conscious consumers and evaluating a revised go-to-market strategy. Following a recent amendment to its credit agreement that provides additional financial flexibility, SNBR is under pressure to return to profitability to maintain compliance. At the recent ICR Conference, the CEO reiterated his target of achieving an 8% pro forma EBITDA margin, with potential to exceed previous peak margins if the company can restart revenue growth. The recently announced lower-price-point bed could help acquire new customers who were previously priced out of the brand, expanding the addressable market. This has the makings of a classic turnaround story, and the chart structure is clearly reflecting this narrative shift. Additionally, the stock carries a relatively high short float, which could amplify upward moves if the turnaround story gains traction.
Technical Outlook: The stock has already delivered an impressive 200% move over the past couple of months, including a breakdown and subsequent reclaim at the beginning of January (we’ve been tracking this setup since the initial consolidation in late December 2025). Currently, the stock is executing a healthy pullback to the 10-day exponential moving average on lower volume than the recent advance, a textbook consolidation pattern. This is not an easy stock to trade given its volatility, but $11.50 represents the line in the sand for a weekly breakout. Holding above this level would confirm the continuation of the uptrend and potentially set up the next leg higher.
INOD: Innodata Inc 📊
What they do: A data engineering and AI services company
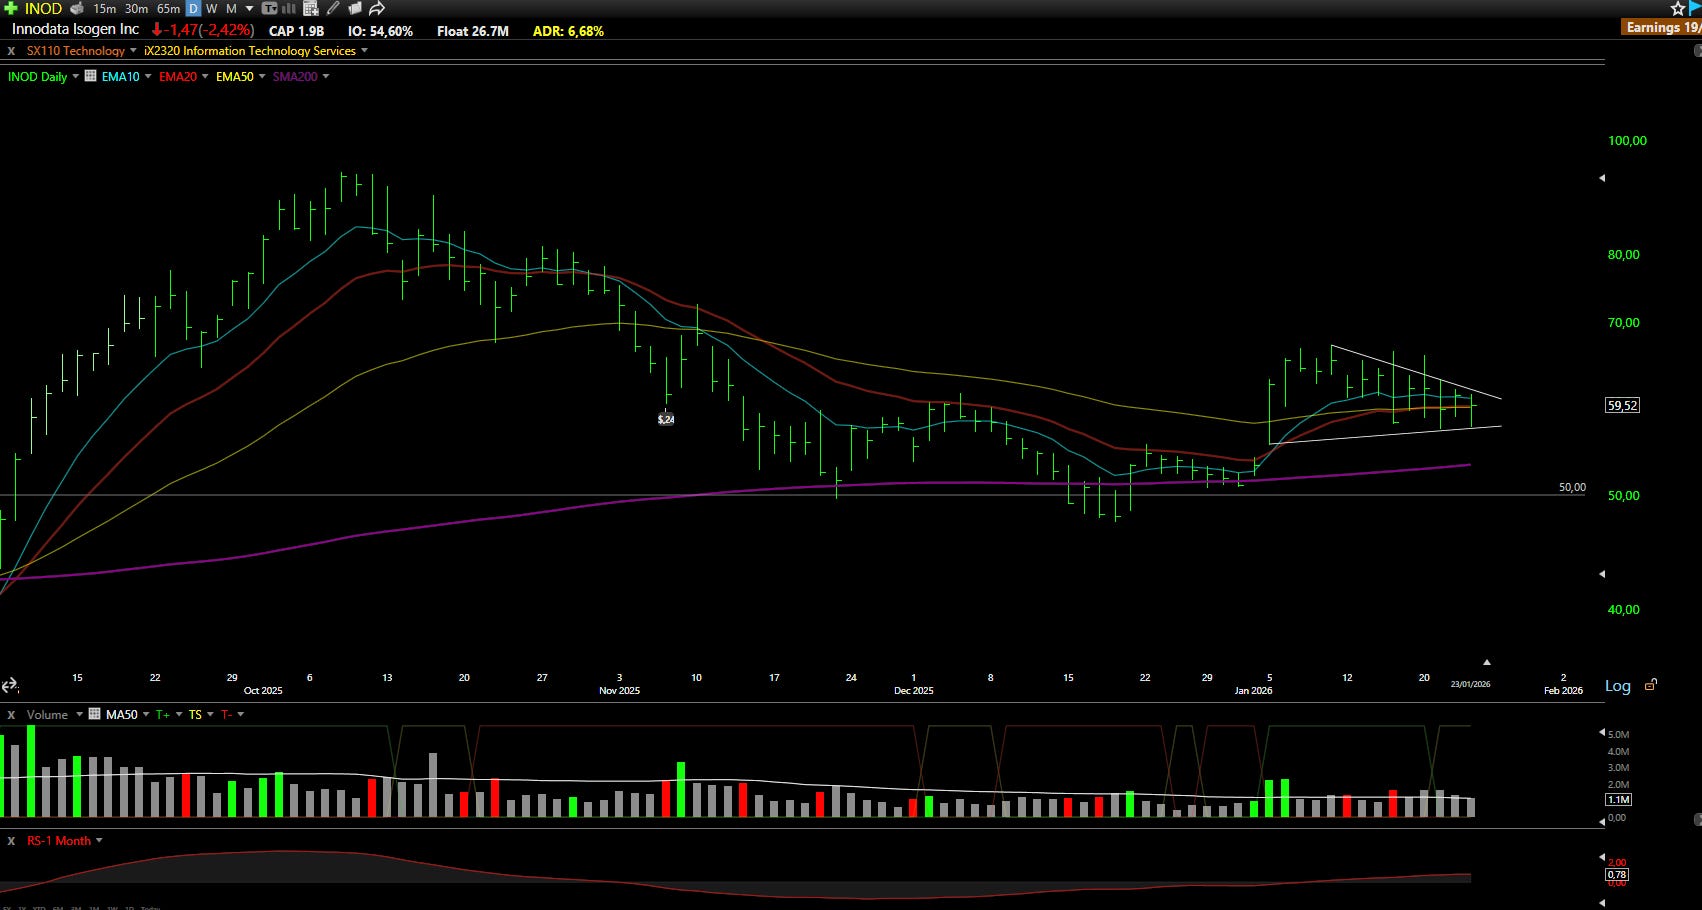
Why watch? Innodata has been experiencing robust growth over the past year, which continued in the latest quarterly report, though the real strength lies in the future outlook provided by management. Q3 revenues reached $62.6 million, representing 20% year-over-year growth, driven primarily by the DDS (Digital Data Solutions) segment, which is the company’s AI-focused business and accounts for 88% of total revenue. The company operates two other segments (Synodex and Agility), but DDS is the clear growth engine. Revenue is predominantly U.S.-based at 84%, and the DDS segment specifically grew 23% year-over-year. The company does maintain high customer concentration, with one client representing 56% of revenue in the latest quarter. INOD’s revenue is projected at $247 million for 2025 and potentially $350 million for 2026, driven by new contract wins and diversification beyond the anchor customer. Management highlighted investments in seven strategic areas: Pre-Training Data, Federal Practice, Sovereign AI, Enterprise AI, Agentic AI, and Modal Safety. Notable contract wins and pipeline opportunities include: verbal confirmation of an expansion with the anchor customer; verbal confirmation of a $6.5 million contract with another large tech company; five new Big Tech customers expected to finalize; a signed $42 million contract for pre-training data; an expected $26 million contract for pre-training data; and a $25 million federal practice contract. One concern is that insiders have been selling shares in recent months, which warrants monitoring.
Technical Outlook: The stock is setting up as another play on the AI and data center theme, with a stronger focus on AI software and data services. INOD recently found a bottom at the $50.00 level, a significant support zone on the weekly chart. All key moving averages are now stacked together near the $60.00 level, which is the most important resistance to watch in the coming week. The stock found support multiple times last week around $57.00, providing a tight entry point with defined risk if $60.00 is broken to the upside. A breakout above $60.00 on volume would confirm the next leg of the uptrend.
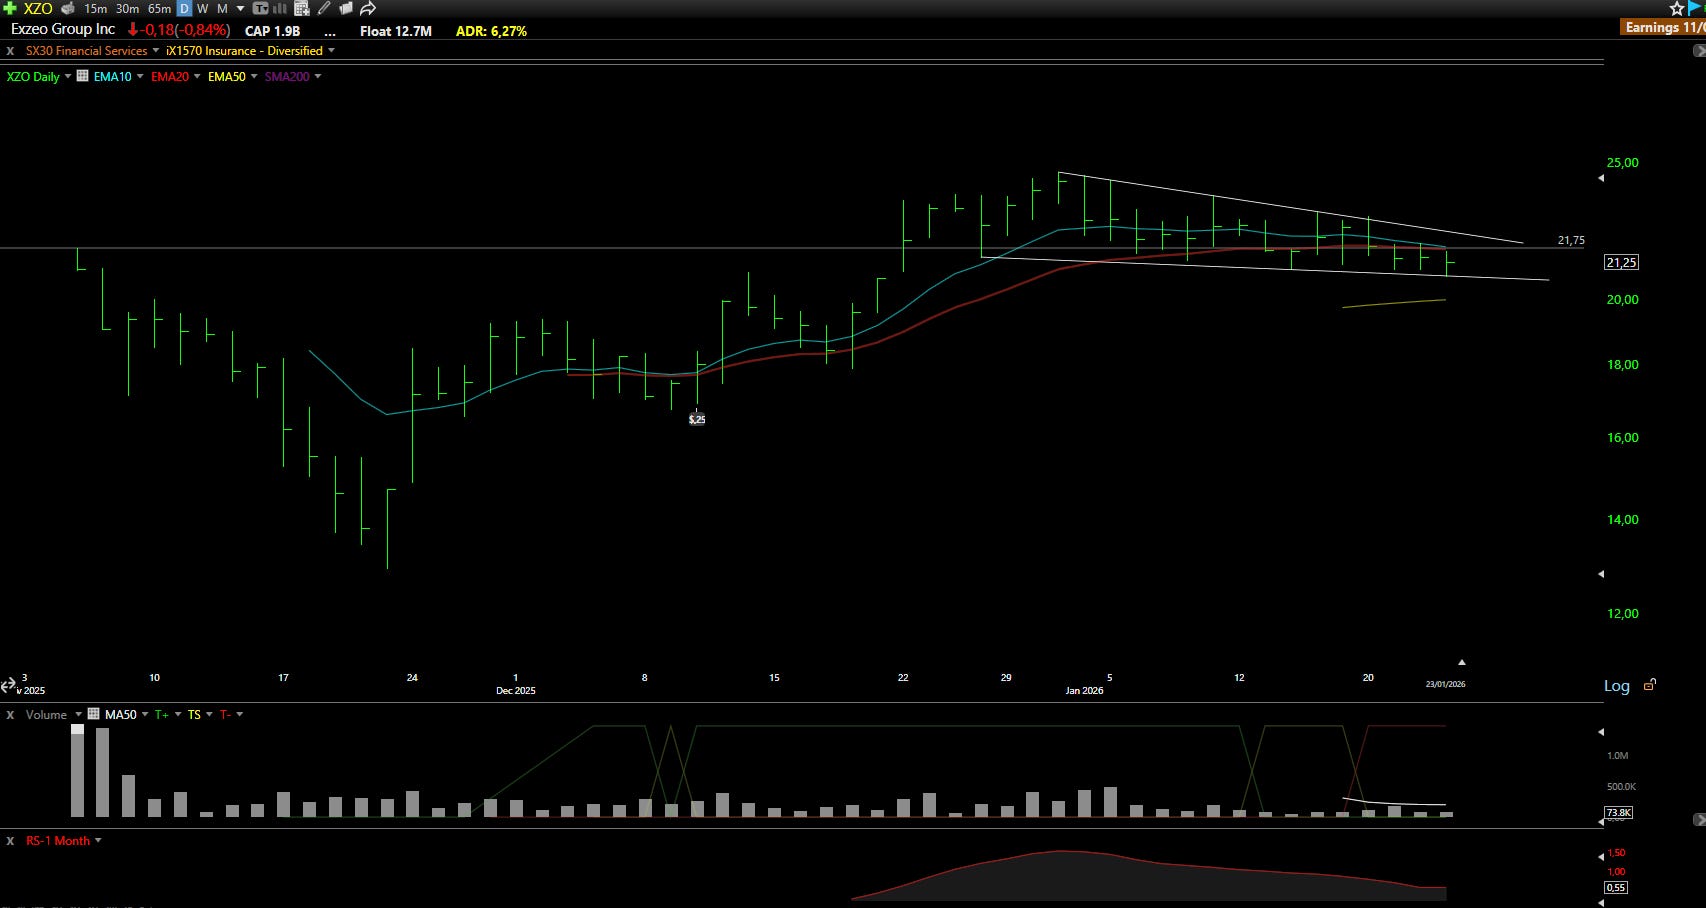
XZO: Exzeo Group Inc ⚠️
What they do: A property and casualty insurance technology company
Why watch? Founded in 2012 within the technology and innovation unit of HCI Group, a leading homeowner insurance underwriter, Exzeo has developed a comprehensive platform that handles all administrative and operational activities for P&C insurance carriers and agents, including quoting, policy management, claims management, and data and financial reporting. The core value proposition centers on advanced underwriting, data analytics, and insurance management solutions, leveraging data and analytical tools to drive superior outcomes for insurance clients. The company recently completed its IPO, and with over 90 million shares outstanding, it carries an equity valuation of approximately $1.89 billion at the offer price. The financial performance trajectory has been dramatic: revenues of $45 million in 2022 (with a $37 million operating loss), nearly doubled to $88 million in 2023 (with $2 million in operating profit), and rose another 52% to $134 million in 2024 (with $38 million in operating profit). Growth has continued at a healthy pace into 2025, with revenues up 80% and GAAP operating margins expanding to 48%. The business fundamentals look compelling given the growth trajectory and profitability, now accompanied by relatively reasonable valuations. The management team is experienced and well-regarded, which is always a positive factor when evaluating newly public companies.
Technical Outlook: The stock is forming its first handle pattern following the typical IPO debut and subsequent downtrend. Currently trading just below the IPO price, the 10-day and 20-day exponential moving averages are acting as resistance. We need to see a clear break above these moving averages before targeting the initial highs around $25.00. This represents a very interesting setup with a low-risk entry point for investors willing to be patient for the breakout confirmation.
HIVE: HIVE Digital Technologies Ltd
What they do: A digital infrastructure company combining large-scale Bitcoin mining operations with an emerging high-performance computing (HPC)
Why watch? HIVE operates Bitcoin mining and HPC facilities across Paraguay, Sweden, and Canada, and is actively investing in HPC data centers to meet growing demand for generative AI, large-scale machine learning, and real-time processing workloads. Management emphasizes that the operational expertise from Bitcoin mining (particularly in power management, cooling systems, and large-scale infrastructure) is transferable to AI infrastructure as they transition from Bitcoin mining facilities to Tier III HPC data centers. However, Bitcoin mining remains the primary value driver in the near term. By November 2025, the company achieved 23 exahash per second (EH/s) in total Bitcoin mining compute capacity, representing over 250% year-to-date growth. In December 2025, HIVE reported mining over 300 BTC. From a valuation perspective, HIVE currently trades at a $600 million market capitalization, with projected revenues of $479.7 million by 2027—a reasonable valuation multiple. The valuation has been compressed partly due to historical shareholder dilution. This is best viewed as a swing trade opportunity rather than a long-term hold, but it offers exposure to both the data center theme and the crypto/blockchain theme. If the cryptocurrency market heats up, this stock could experience a second significant run similar to autumn 2025.
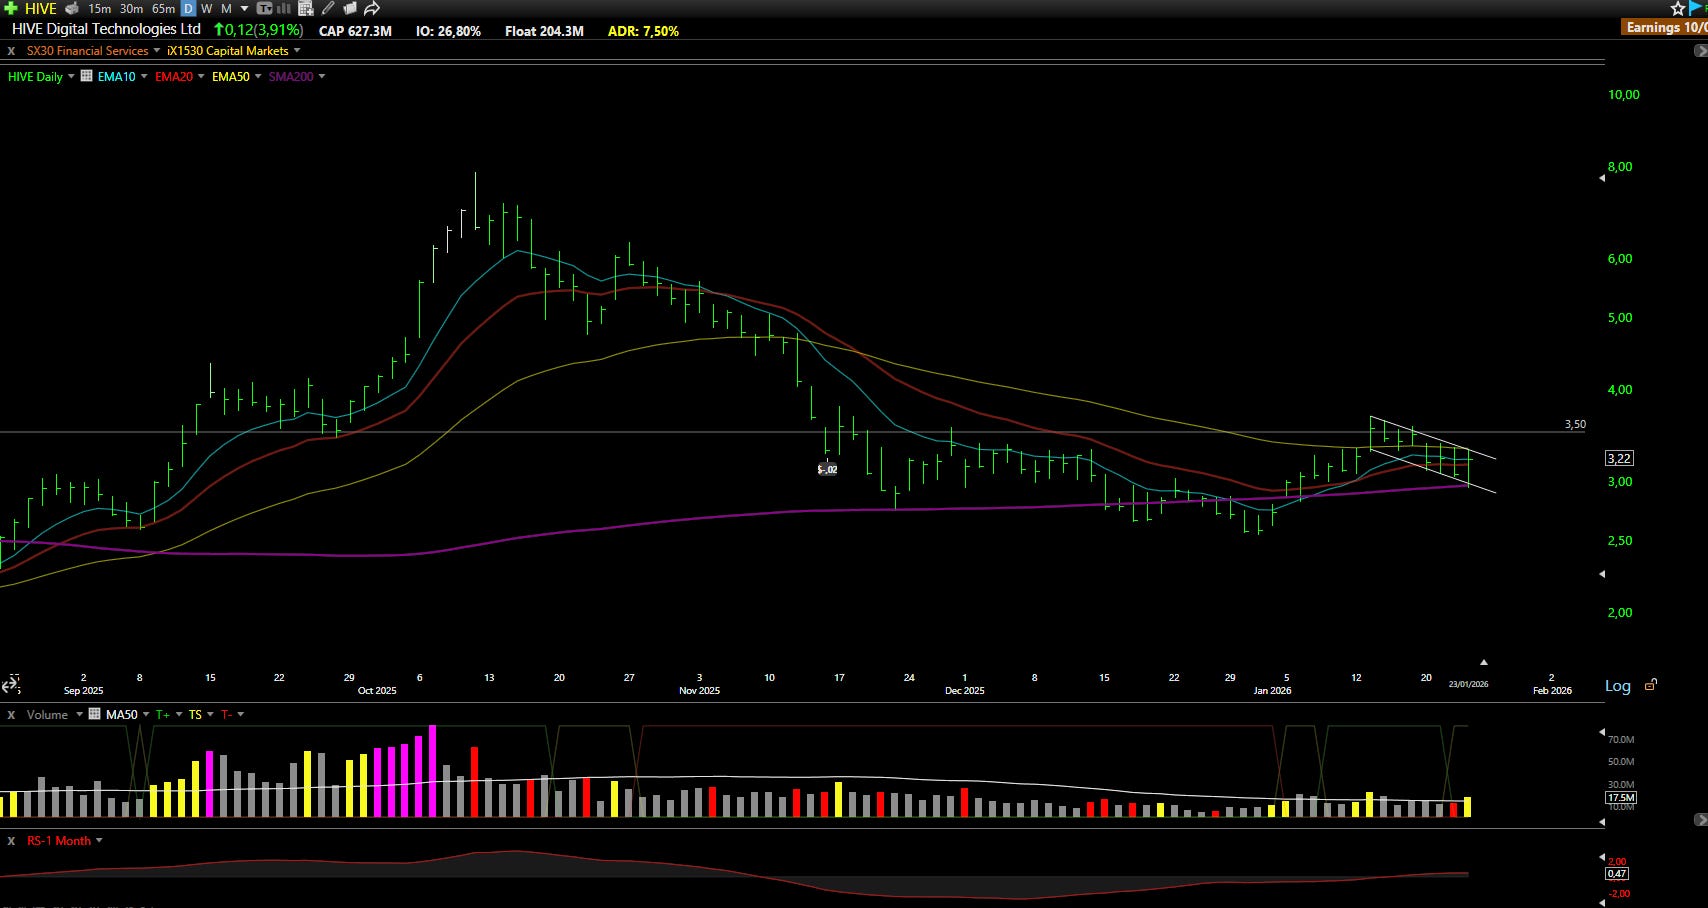
Technical Outlook: The stock found clear support last week at the 200-day simple moving average and has since moved above both the 10-day and 20-day exponential moving averages, though it remains below the 50-day EMA, which is acting as current resistance. The price is forming a tight flag pattern, and you can anticipate a breakout here with relatively low risk. However, the key level to watch is the weekly resistance at $3.50. A breakout above this level on volume could propel the stock higher with an initial target around $5.00.
ZBIO: Zenas BioPharma Inc 📊
What they do: A clinical-stage biopharmaceutical company developing novel immunology therapies
Why watch? Zenas BioPharma remains a compelling opportunity despite a sharp stock decline following its Phase 3 INDIGO trial results. While Obexelimab met the primary endpoint in IgG4-related disease (IgG4-RD), the stock sold off because cross-trial comparisons with Amgen’s UPLINZA (inebilizumab) showed less favorable risk reduction of disease flares. However, there is significant recovery potential as the company prepares to file a Biologics License Application (BLA) for Obexelimab in IgG4-RD patients in Q2 2026, followed by a Marketing Authorization Application (MAA) in the second half of 2026. Additionally, positive Phase 2 data from the Moonstone trial using Obexelimab to treat relapsing multiple sclerosis (RMS) patients represent another potential catalyst. Zenas BioPharma maintains a solid balance sheet with approximately $300 million in cash, cash equivalents, and investments. In October 2025, the company raised $120 million through a private placement at $19.00 per share, not far from current trading levels. Most encouraging is the recent insider buying activity: insiders purchased shares in October 2025 and January 2026, and the CEO personally bought over $1.5 million worth of shares on January 7, 2026: a strong vote of confidence in the company’s prospects.
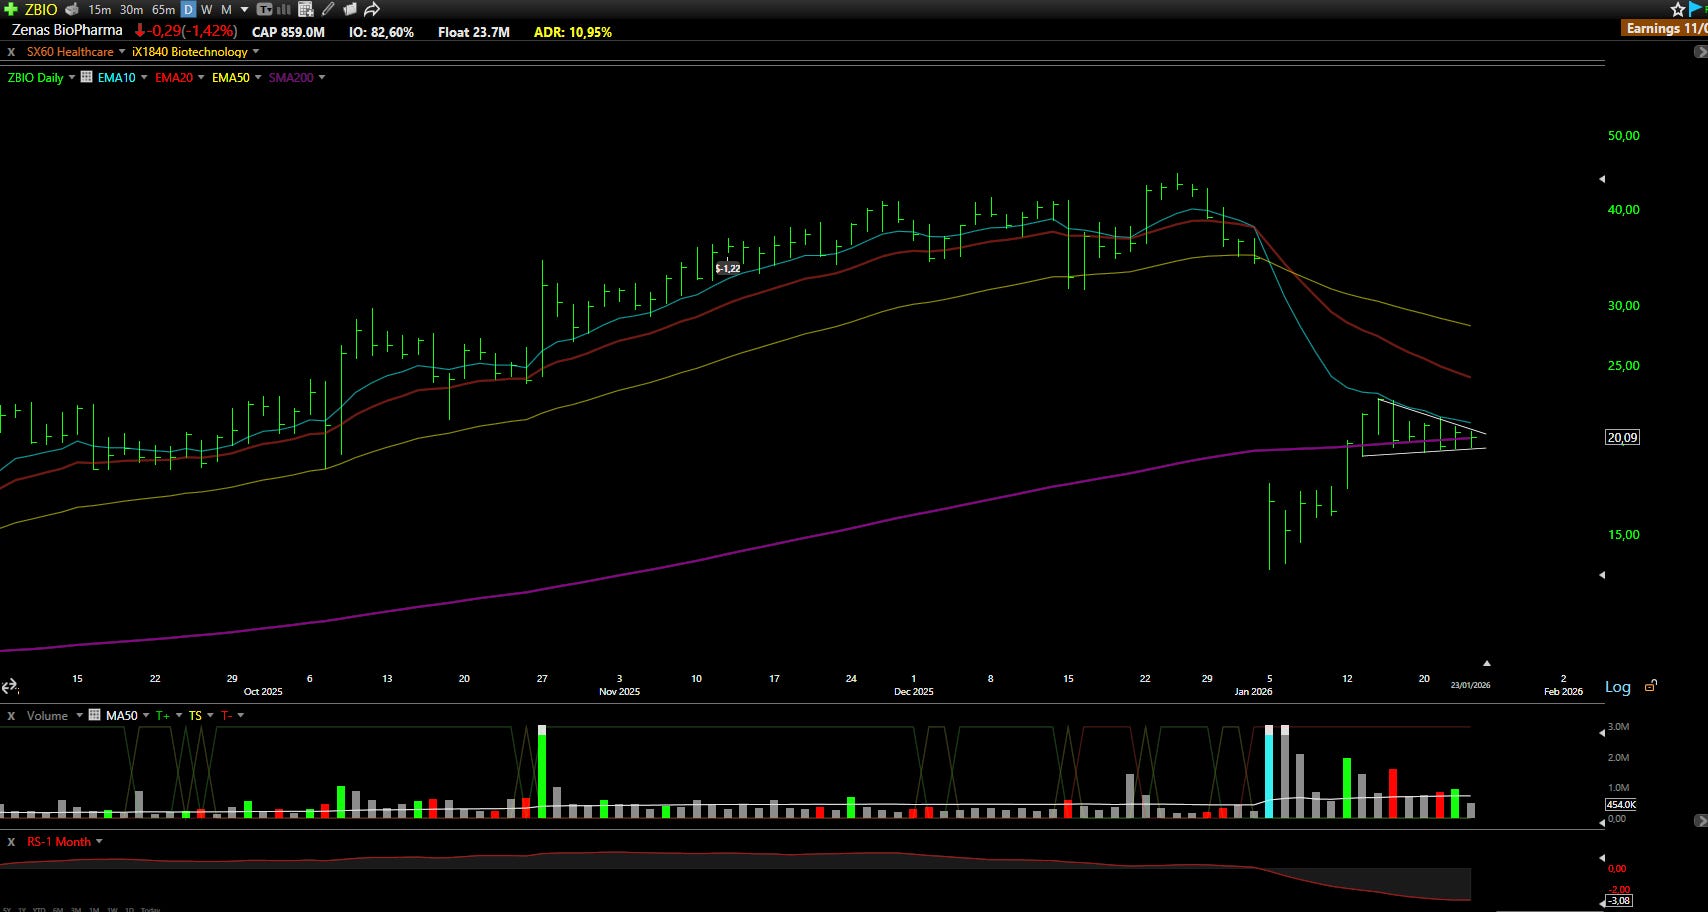
Technical Outlook: The company is forming one of the most attractive low-risk consolidation patterns available in the biotech sector. The stock is finding support at the 200-day simple moving average, offering a very tight risk/reward setup. Combined with a solid underlying story, strong insider buying, and recent IPO status, this has the ingredients for a potential breakout. If the consolidation resolves to the upside, the risk-reward profile is exceptionally favorable for patient investors.
These tickers below didn’t make the main cut, but they’re on our radar for a reason. We’ve vetted them; now you decide if they fit your game.
More opportunities, less noise.
⚡📋Scanned Stocks: Quick Picks
EKSO - Ekso Bionics Holdings Inc
XTIA - XTI Aerospace Inc
ABAT - American Battery Technology Company
FND - Floor & Decor Holdings Inc
RMTI - Rockwell Medical Inc
"The most contrarian thing of all is not to oppose the crowd but to think for yourself."
Peter Thiel
Disclaimer: This analysis is for informational purposes only and should not be considered financial advice. Always conduct your research and consult with a licensed financial advisor before making investment decisions.